Showing posts with label BAT. Show all posts

Tuesday, February 08, 2022

BAT: Green Shots of Recovery

Result Update

For QE31/12/2021, BAT's net profit dropped 9.4% q-o-q or 2.0% y-o-y to RM71.5 million while revenue rose by 40.6% q-o-q or 30.5% y-o-y to RM862 million.

As explained in its press release, BAT "performed remarkably in 2021 with the volume growing for the first time since 2002, profit growing for the first time since 2015 and strong quarter on quarter improvement in our financial performance. The growth momentum comes from an increase in volume and share of market which, in turn, improved revenue and profit from operations. The volume increase was mainly due to the reduction in the tobacco black market by 6.1% compared to FY2020. This growth in volume led to a revenue of RM2.6 billion for FY2021 compared to RM2.3 billion in FY2020 (growth of 14%) and a profit from operations of RM411 million compared to RM346 million in FY2020 (increase of 19%)."
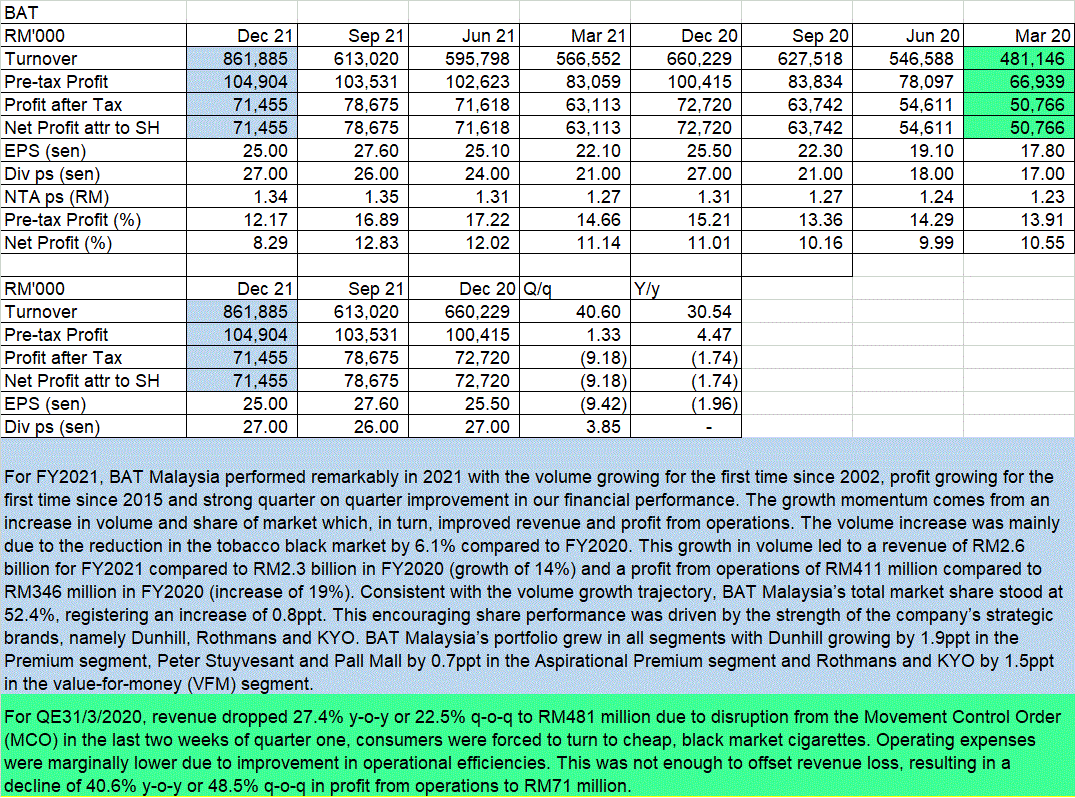

Table 1: BAT's last 8 quarterly results

In fact, the improved performance was seen mainly in the last quarter, ie. QE31/12/2021. See the sharp spike in the revenue in the graph below.


Graph: BAT's last 53 quarterly results

However, BAT's bottomline did not increase because the company made additional charge-off in the form of inventories write-down and restructuring expenses. See the table below.

Table 2: Changes in P&L items in QE31/12/2021, QE30/9/2021 & QE31/12/2020

Valuation

BAT (closed at RM12.40 today) is now trading at a PER of 12.4 times (based on the last 4 quarters' EPS of 99.8 sen). BAT has paid out quarterly dividend payment totaling of 98 sen over the past 4 quarters; thus giving a Dividend Yield of 7.9%. Based on the above, BAT is considered fairly attractive for a recovery play.

Technical Outlook

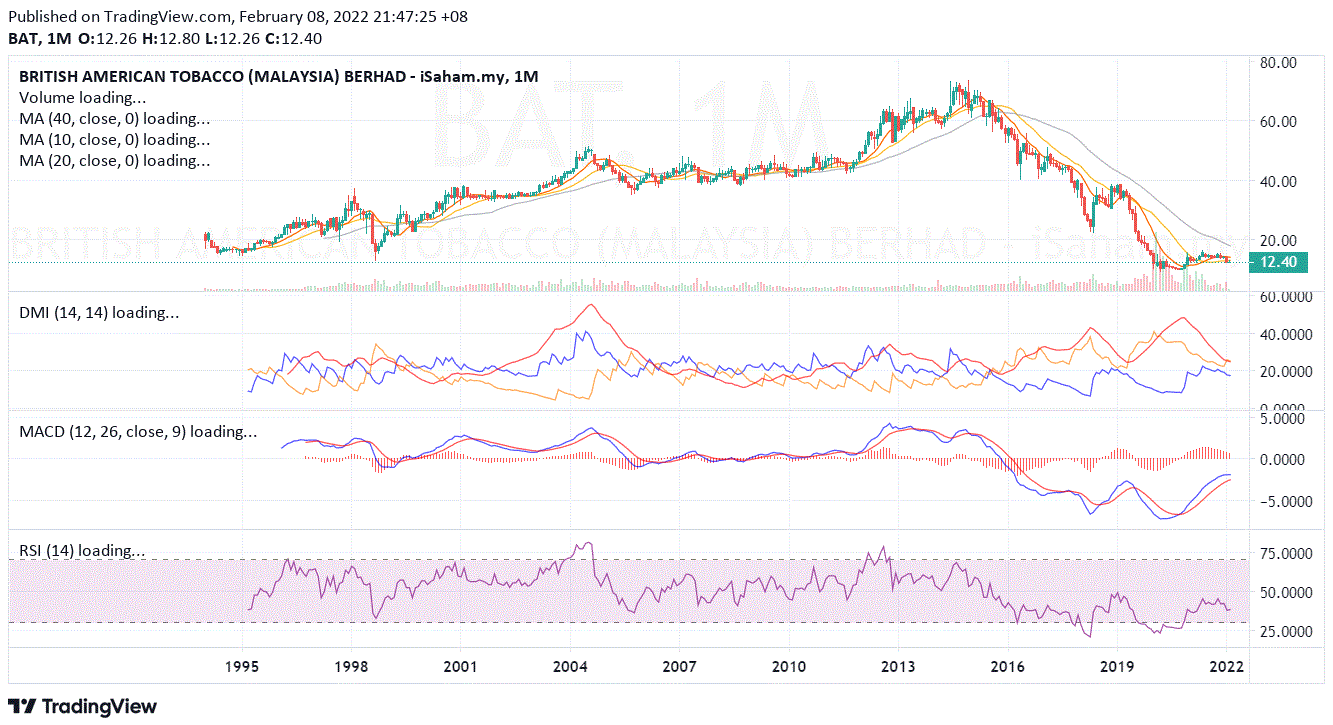
BAT dropped from its high of about RM74.00 in Dec 2014 to a low of RM9.20 in Mar 2020. In the last 12-13 months, the share prices were well-supported at the horizontal line at RM12.20-12.30. 


Chart 1: BAT's monthly chart as at Feb 8, 2022 (Source: isaham.my)

Chart 2: BAT's daily chart as at Feb 8, 2022 (Source: isaham.my)

Conclusion

Based on an improved financial performance, BAT is a good stock for a recovery play. This is notwithstanding its technical outlook remains bearish as the downtrend has yet to be reversed.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Tuesday, May 26, 2020

BAT: Sales Dropped Sharply due to MCO Disruption

Result Update

For QE31/3/2020, BAT's net profit dropped 46% q-o-q or 43% y-o-y to RM51 million while revenue dropped by 27% q-o-q or 23% y-o-y to RM481 million.

The sharp drop in revenue was attributed to disruption from the Movement Control Order (MCO) in the last two weeks of quarter one, which caused consumers to turn to cheap, black market cigarettes. Operating expenses were marginally lower due to improvement in operational efficiencies but this was not enough to offset revenue loss, resulting in a decline of 48% q-o-q or 41% y-o-y  in profit from operations to RM71 million. 


Table: BAT's last 8 quarterly results


Graph: BAT's last 53 quarterly results

Valuation

BAT (closed at RM11.72 last Friday) is now trading at a PER of 10.9 times (based on the last 4 quarters' EPS of 107.8 sen). BAT has paid out quarterly dividend payment totaling of 105 sen over the past 4 quarters; thus giving a Dividend Yield of 9.0%. Though its valuation looks attractive, the concern for many investors is whether BAT can stop the continuous decline in both revenue and profits, since the MCO period covers the whole of the next quarter. Only time will tell.

Technical Outlook

BAT broke below its medium-term uptrend line, SS at RM12.60. It may slide to the horizontal line at RM11.00.


Chart: BAT's daily chart as at May 22, 2020 (Source: Malaysiastock.biz)

Conclusion

Based on a weak financial performance and a bearish technical outlook, BAT may be a contrarian stock for long-term investment. All the negative factors could be substantially factored in the share price which is trading at a PER of 10.9 times and a dividend yield of 9.0%.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Tuesday, May 05, 2020

BAT: Rising from the Ashes

BAT share price has been dropping for so long that many investors have learned to avoid the stock. See the monthly chart below.

Chart 1: BAT's monthly chart as at May 4, 2020 (Source: Malaysiastock.biz)

The share price decline is brought on by the decline in revenue and profits. I have constructed a graph of BAT's rolling 4 quarters' revenue and profits, excluding lumpy restructuring expenses, from Dec 2007 up to Dec 2019.

Graph: BAT's rolling 4-quarter revenue and profit from Dec 2007 to Dec 2019

The latest quarterly results will be announced in 3 weeks' time. It will probably show further decline in revenue and profits. If that panned out, we can expect share prices, which have rallied from RM10 to RM13, may renew their decline. Why are investors buying into BAT shares now or in the near future?

The Investment Case for Buying BAT 

1) The share price has broken above the medium-term downtrend line, RR at RM12.00.


Chart 2: BAT's daily chart as at May 4, 2020 (Source: Malaysiastock.biz)

2) It is a well-managed multinational company. The downside is its products pose health risks which led to legal restrictions being imposed which curtailed its consumption.

3) BAT is trading at a fairly attractive valuation with PER at 10.9 times an dividend yield at 8.9%.

4) Due to poor enforcement, illegal cigarettes are widely available in Malaysia, and these compete very successfully against BAT's products as their selling prices are substantially lower. The result of this illegal trades is lower sales for cigarettes manufacturers, leading to plant shutdown and loss of employment. An example is BAT shutting down its main factory in Petaling Jaya, and moving its production to Indonesia. In addition, Malaysian government loses more than RM5 billion annually in term of duties/taxes collection due to the illegal trades (here).

In the Covid-19 environment where government income is sharply lower and employment opportunity is scare, a case can be made that the government will finally crack down on the illegal trades in cigarettes. This will lead to higher income flowing to the government coffers and greater employment opportunities for Malaysians. Consequently, we can expect increased sales and profits for the legal cigarette manufacturers such as BAT further down the road.

Conclusion

Based on technical and fundamental consideration, I believe BAT is a good stock for medium to long-term investment.

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Friday, February 21, 2020

BAT: What Are They Smoking?

As at 9:15 a.m., BAT made a high of RM14.10. This strong rally could be due to its results announcement for QE31/12/2019, which is the 4Q2019. 

From the table below, we can see that the quarterly revenue, profits and dividend dropped when compared to those of 4Q2018 (see point 1). In addition, its full-year revenue, profits and dividend also dropped when compared to FY2018 (see point 2).

Table: BAT's last 8 quarterly results

Technically speaking, BAT has surpassed its downtrend line at RM13.00. This may signal the end of its downtrend but it may not neccesarily lead to an uptrend rally anytime soon.

Chart: BAT's daily chart as at Feb 20, 2020 (Source: Malaysiastock.biz)

Based on the above, I think the current sharp rally may not sustain.

Thursday, May 30, 2019

TM & BAT: Different Strokes for Different Stocks

During the lunch break, TM announced its results for QE31/3/2019. Its net profit rose 342% q-o-q or 96% y-o-y to RM308 million. Revenue dropped 10% q-o-q or 2% y-o-y to RM2.779 billion. As at 3.30 pm, TM share price rose 61 sen (or 22%) to RM3.33.

Table 1: TM's 8 quarters' P&L

Looking at the slightly weaker revenue and the big jump in profits which came after a big drop 2 quarters ago, the excitement about TM's performance looks unjustified.


Graph 1: TM's 45 quarterly P&L

On the other hand, BAT has undergone the opposite treatment when it announced its result for QE31/3/2019 after market close on May 28. On opening the next day (May 29), BAT (closed at RM33.44 the day before) started dropping. As at 3.30 pm today, BAT was trading at RM28.94. In total, BAT lost 13.5%.


Table 12; BAT's 8 quarters' P&L


Graph 2: BAT's 45 quarterly P&L

In my opinion, TM is over-rewarded for the "good" result while BAT is over-punished for the "bad" result.

Thursday, July 19, 2018

BAT: Green Shoots of Recovery Sighted

Result Update

For QE30/6/2018, BAT's net profit rose 23% q-o-q but dropped 16% y-o-y to RM96 million while revenue dropped by 9% q-o-q or 17% y-o-y to RM638 million.

Revenue rose 6.5% q-o-q due to volume growth of 4.8% versus the first quarter of 2018. The Group registered a market share of 57.2% (new reporting vs. 53.5% at old reporting) in the second quarter of 2018 (based on restated legal market share), despite a 1.0ppt-decrease in market share registered by Dunhill to 39.7% from 40.7% in the first quarter 2018 (Note: The correction of 1.0ppt versus preceding quarter was partially due to the growth of Value for Money (VFM) segment and the continuous pressure of high levels of illegal and quasi legal (illegal tax stamps) trade.

Value for money brands increased its market share by 0.2ppt and Aspirational Premium brands increased their market share marginally by 0.2ppt.  This improving volume performance was the main driver for the second quarter revenue and gross profit growth of 6.5% (RM41 million) and 8.7% (RM 17 million) respectively, when compared to the preceding quarter.

Operating expenses were 9.7% (or, RM6 million) lower than preceding quarter. Operating expenses dropped due to lower overhead costs driven by cost base transformation initiatives the Group has undertaken and timing of other operating expenditure. As a result, Profit from Operations in the second quarter of 2018 grew 17.1% (RM22 million) when compared to the preceding quarter.


Table: BAT's last 8 quarterly results

BAT's revenue grew for the first time after declining for the past 3 years. Profits have been declining in a zig-zag fashion - with the magnitude determined by provisioning exercise or timing of expenses.


Graph: BAT's last 45 quarterly results

Valuation

BAT (closed at RM33.68 yesterday) is now trading at a PER of 22 times (based on the last 4 quarters' EPS of 151.7 sen). BAT has paid out quarterly dividend payment totaling of 154 sen over the past 4 quarters; thus giving a Dividend Yield of 4.6%. It is encouraging to note that dividend increased to 35 sen from 33 sen in QE31/3/2018.

Technical Outlook

BAT is still in a long-term downtrend line, with resistance at RM37.80-38.00.


Chart 1: BAT's weekly chart as at July 19, 2018 (Source: Malaysiastock.biz)


Chart 2: BAT's monthly chart as at July 19, 2018 (Source: Shareinvestor.com)

Conclusion

Based on possible turnaround in financial performance and increased dividend payment, BAT is now worth considering for long-term investment. However its next upleg will only begin once BAT managed to break above its downtrend line at RM37.80-38.00.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Tuesday, May 22, 2018

BAT: Profits Improved Slightly On Lower Revenue

Result Update

For QE31/3/2018, BAT's net profit rose 23% q-o-q but dropped 16% y-o-y to RM96 million while revenue dropped by 9% q-o-q or 17% y-o-y to RM638 million.

Revenue dropped by 9% q-o-q due to decline in sales volume of 3.0% compared to immediate preceding quarter. The Group registered market share growth from 53.9% in the fourth quarter of 2017 to 54.7% in the first quarter of 2018, as Dunhill registered a 0.5ppt-increase in market share to 38.2% while Value for Money brands increased its market share by 1.2ppt to 30% and Aspirational Premium brands increased their market share marginally from 42 to 44% (despite a drop in volume). As a result of the lower volume performance, BAT's gross profit dropped 5.3% q-o-q. Operating expenses were 39.4% (RM40.6 million) lower than preceding quarter- due to the absence of provision of impairment for prepaid excise duties (compared to RM21 million provided in the preceding quarter), lower distribution & marketing cost and timing of other expenses. Lower operating expenses had more than offset the drop in gross profit- leading to a 23.2%-increase in operating profit. Higher operating profit flowed thru to higher PBT, PAT & NP.


Table: BAT's last 8 quarterly results

BAT's revenue has been on a decline for the past 3 years, with no sign of bottoming out. Profits have been declining in a zig-zag fashion - with the magnitude determined by provisioning exercise or timing of expenses.


Graph: BAT's last 45 quarterly results

Valuation

BAT (closed at RM33.40 yesterday) is now trading at a PER of 20 times (based on the last 4 quarters' EPS of 164.70 sen). BAT has paid out quarterly dividend payment totaling of 162 sen over the past 4 quarters; thus giving a Dividend Yield of 4.85%. If BAT's revenue & profits were to stabilize, the stock will be an attractive stock as these multiples are fairly attractive for a well-managed MNC.

Technical Outlook

BAT is likely to be still in a long-term downtrend. It is now pressing against the 40-week EMA line at RM33.20.


Chart 1: BAT's weekly chart as at May 21, 2018 (Source: Shareinvestor.com)

The immediate support & resistance are at RM32 & RM36.


Chart 2: BAT's daily chart as at May 21, 2018 (Source: Shareinvestor.com)

Conclusion

Based on a still weak financial performance and a still bearish technical outlook, BAT is a stock to be purchased with caution. However once the company's revenue and profits have made a bottom, it could be a good stock to invest in as it is a well-managed company.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Thursday, April 19, 2018

BAT: The Bottom could be in.


Today we are again seeing huge volume for British American Tobacco Bhd (BAT). As at 2:45pm, the volume traded for BAT was 1.67 million. BAT (at RM23.90 then) was up RM1.14 from yesterday close. I denoted this as “C”.

This huge volume and the price rally is the opposite of 2 previous days of huge volume in mid-Feb (denoted as “A”) and on April 17 (denoted as “B”). In the sell-off in mid-February, the share price dropped from RM33.00 to RM29.50. The sell-off on April 17 did not cause a noticeable drop in the share price.

These 3 days of huge volume suggests the presence of selling pressure in the market. The change in the price movement – from price decline to relative price stability and finally to price rally - suggest that BAT may finally have dropped to a price level that is cheap enough that we are witnessing a competition among the interested buyers. We can see it very clearly that these buyers are competing and it caused the share price to rally.

Chart 1: BAT's daily chart as at April 19, 2018_2.45pm (Source: Shareinvestor.com)

BAT is a well-managed MNC with a history of profit that stretches back as far as Bursa’s record is available. The last 2 years of lower profit was due mainly to the cost of restructuring as BAT closed its manufacturing plant and shifted its supply chain to a neighbouring country. This is a good opportunity to get into a well-managed company trading at very undemanding multiple.

Chart 2: BAT's monthly chart as at April 19, 2018_2.45pm (Source: Shareinvestor.com)

Graph: BAT's last 18 years revenue, profits and EPS/DPS

I think BAT is now attractive enough to buy since its peak at RM73 in late 2014. BAT’s PER is 13.8 times while its dividend yield is at a eye-popping 7.1%. I recommend this as a long-term BUY.

Note: For more on BAT, go to my earlier post.

Thursday, February 15, 2018

BAT: Earnings Plummeted


Result Update

For QE31/12/2017, BAT's net profit dropped 45% q-o-q or 74% y-o-y to RM78 million while revenue dropped by 8% q-o-q or 17% y-o-y to RM700 million.

Revenue decreased by 7.5% due to decline in sales volume of 3.0% compared to immediate preceding quarter as well as decline in higher price segment. The Group registered market share growth from 53.6% in the third quarter to 53.9% in the fourth quarter of 2017 with Dunhill registering a 0.7%-decrease in market share to 37.7% while Aspirational Premium brands, Peter Stuyvesant and Pall Mall, increased their market share to 10.9%. The group entered the Value For Money (VFM) segment in October 2017 through the introduction of Rothmans. In the fourth quarter of 2017, Rothmans stood at 1.8% market share and was becoming the fastest growing brand within the VFM segment, exiting 2017 at 2.8% market share.

Operating expenses were 39.1% (RM33 million) higher than preceding quarter. Operating expenses, excluding the provision of impairment for prepaid excise duties of RM21 million, increased 14.9% (RM13 million) versus immediate preceding quarter.

After deducting restructuring expenses of RM1.4 million which consisted of on-going cost of the project and outplacement programs, operating profit declined 44.4% (RM84.1 million) when compared to the immediate preceding quarter.


Table 1: BAT's last 8 quarterly results

BAT's revenue and profits have been on a decline for the past 3 years. There is no sign that these have hit hot the bottom.


Graph: BAT's last 44 quarterly results

Valuation

BAT (closed at RM29.06 yesterday) is now trading at an adjusted PER of 16.9 times (based on the last 4 quarters' EPS of 172.6 sen). BAT has paid out quarterly dividend payment totaling of169 sen; thus giving a Dividend Yield of 5.8%. If BAT's revenue & profits were to stabilize, the stock will be an attractive stock as these multiples are fairly attractive for a well-managed MNC.

Technical Outlook

BAT broke its long-term uptrend line, SS at RM52 in April 2016. In the last 2 months, it broke the psychological support at RM40 as well as the horizontal line at RM38. Today it broke another psychological support of RM30.00. Its next support is at the horizontal line at RM27.


Chart: BAT's monthly chart as at Feb 14, 2018 (Source: Shareinvestor.com)

Conclusion

Based on dateriorating financial performance and bearish technical outlook, BAT is a stock to be avoided. However once the company's revenue and profits have made a bottom, it could be a good stock to invest in as it is a well-managed company.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Friday, April 21, 2017

BAT: Earning Recovery Not In Sight Yet

Result Update

For QE31/3/2017, BAT's net profit dropped 62% q-o-q or 34% y-o-y to RM114 million while revenue dropped by 8% q-o-q or 24% y-o-y to RM771 million. Revenue declined 24% y-o-y (or, RM 250 million) in line with volume decline, leading to a Gross Profit deterioration of 27.5% y-o-y (RM97 million).

Operating Expenses dropped 18.1% (or, RM22 million), attributed to timing of spends, lower recharges from related entities as well as overhead savings from cost efficiency initiatives the Group has undertaken.

During the same period, the Group has further recorded a one-off restructuring expenses of RM1.6 million which consists of the on-going cost of the project, outplacement programs and one-off expenses associated with the storage and transfer of unprocessed leaf and raw materials.

As a consequence, the Group registered a decline of 32.8% (or, RM77 million) and 32.3% (or, RM75 million) in Profit from Operations and Profit before Tax respectively.


Table 1: BAT's last 8 quarterly results


Graph: BAT's last 41 quarterly results
  
Valuation

BAT (closed at RM47.06 yesterday) is now trading at an adjusted PER of 20.2 times (based on the last 4 quarters' EPS of 232.7 sen). BAT has paid out quarterly dividend payment totaling of 217 sen; thus giving a Dividend Yield of 4.6%.

Technical Outlook

BAT is trying to find a base at RM40-50 level. With monthly MACD nearly hooking up and downtrend momentum peaking, the bottom is near.


Chart: BAT's monthly chart as at April 20, 2017 (Source: Shareinvestor.com)

Conclusion

Based on weak financial performance and unattractive valuation, BAT is not a good stock for long-term investment. With a tentative bottom in sight, BAT's rating is revised from a SELL to a HOLD.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Thursday, March 30, 2017

BAT: Another Day, Another Shoe Drop!!


Yesterday BAT went below its overnight price at around 9.41am. It continued its decline throughout the day and closed at RM45.44. It was the top loser on Bursa- losing RM2.46 or 5%!

A quick check revealed that the likely causes for the selldown are the concern about the likelihood of prices of cigarettes going up from RM17 presently to RM21.50 (here) and the proposal to raise the minimum age for buying cigarettes from 18 to 21 (here). These measures are supposedly intended to reduce the consumption of cigarettes- which is all very good. But, the government must do more to curb the trade in illicit cigarettes. Higher cigarette price has been a boon to that trade which saw the percentage of illicit cigarettes capturing more than 50% of total cigarettes consumed in Malaysia. If we don't tackle this trade, we will collect less revenue from both corporate tax & duties while the incurring higher medical cost to treat various ailments that resulted from long-term smoking but I digress.


Source: CIMB

Now, back to BAT. The chart looks like this:


Chart: BAT's weekly chart as at Mar 29, 2017 (Source: Kenanga)

BAT is in a downtrend (RR) which is accelerating (R1-R1). The area between RM41-43 is the support for the stock. If you are an investor looking for a decent income stock, you may be tempted to buy at that level. If you are a medium-term speculator who viewed the price movement as a downward channel, you may be tempted to buy at the lower line, R2-R2 (around RM38) and hoping for a rebound to sell at the upper line, R1-R1 (at RM49).
 
For now, I maintain my existing rating for BAT, i.e. a SELL. However it can be considered as a Trading BUY for a rebound play if it drops to RM39.00-40.00 (the support of a long-term uptrend line). 

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Friday, February 17, 2017

BAT: Earnings Rebounded On One-Off Gain

Result Update

For QE31/12/2016, BAT's net profit rose 41% q-o-q or 53% y-o-y to RM299 million while revenue dropped by 10% q-o-q or 21% y-o-y to RM841 million. Revenue declined 10% q-o-q and Gross Profit declined 17.1% q-o-q due to 33.3%-reduction in contract manufacturing volumes and 4.3%-drop in domestic and duty-free volume.

Operating Expenses rose 10.5% q-o-q largely driven by higher marketing expenditure due to timing of spend, which was partially offset by lower recharges. During the same period, the Group recorded a restructuring income of RM132 million which consists of a gain from the disposal of the land and building which the factory operation is located (RM159 million) which was partially offset by provision for employee redundancy related costs (RM8 million), impairment of asset (RM3 million), provision for obsolete raw materials (RM4 million) and leaseback rental (RM13 million).

As a result, Profit from Operations increased by 27.7% (RM69 million) when compared to the previous quarter. If the impact of one-off restructuring expenses and income is excluded, Profit from Operations would actually decline by 25.7% (RM64 million).


Table 1: BAT's last 8 quarterly results


Chart 1: BAT's last 40 quarterly results
  
Valuation

BAT (closed at RM48.78 yesterday) is now trading at an adjusted PER of 19.4 times (based on the last 4 quarters' adjusted EPS of 252 sen). BAT has paid out quarterly dividend payment totaling of 232 sen; thus giving a Dividend Yield of 4.8%.

When compared to HEIM & Carlbg, BAT's PER & DY are less attractive. HEIM & Carlsbg have higher DY of 5.7% & 5.1% and lower PER of 18.3x & 18.6x respectively.

Technical Outlook

BAT has recently tested its long-term uptrend line, SS support at RM40.00-41.00 and then rebounded.


Chart 1: BAT's monthly chart as at Feb 16, 2017 (Source: MalaysiaStock.Biz)

BAT's upside is capped by the intermediate downtrend line, RR at RM49.00-50.00.


Chart 2: BAT's weekly chart as at Feb 16, 2017 (Source: MalaysiaStock.Biz)

Conclusion

Based on the poorer financial performance and unattractive valuation, BAT's current rating as a SELL is maintained.However if BAT were to slide to RM49.00-50.0039.00-40.00, it could be a Trading BUY for a rebound play.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Wednesday, July 27, 2016

BAT: Earnings Plummeted

Result Update
For QE30/6/2016, BAT's net profit dropped by 72% q-o-q or 78% y-o-y to RM48 million while revenue dropped by 6% q-o-q or 12% y-o-y to RM963 million. This is the first time since 2011 that BAT's quarterly revenue had dropped below the RM1 billion mark!

The drop in revenue was due to the following:
  • Group’s Domestic and Duty Free recorded a q-o-q decline of 9.1% due to the continued impact of the November 2015 excise led price increase as well as reduced consumption during the fasting month
  • Contract Manufacturing volumes declined 11.1% q-o-q
The weak volume performance coupled with inflationary increases in costs and timing differences in expenditures, caused the revenue and gross profit to decline q-o-q by 5.7% and 8.1% respectively.

During the same period, the Group has made a provision for restructuring expenses of RM86 million in relation to the winding down of its factory operations. As a result, Profit from Operations declined 49.6% q-o-q to RM117million. Excluding the impact of one-off restructuring expenses above mentioned, Profit from Operations registered a decline of 13.1% (or, RM31 million) versus the first quarter of 2016.

Net profit dropped by 72.7% q-o-q due to higher effective tax rate of 36% (as compared to 25% previously) as restructuring expenses in relation to the cessation of factory operations were non-deductible.


Table 1: BAT's last 8 quarterly results


Chart 1: BAT's last 38 quarterly results

Below, I tabulated BAT's last 8 quarters' P&L after excluding the restructuring expenses of RM86 million. While the drop in warnings is still bad, it was not so disastrous. Net profit would be lowered by 12% q-o-q or 29% y-o-y to RM152 million. EPS would improve from 236.sen to 273 sen.


Table 2: BAT's last 8 quarterly results (Restructuring expenses in QE30/6/2016 excluded)


Chart 2: BAT's last 38 quarterly results (Restructuring expenses in QE30/6/2016 excluded)
  
Valuation

BAT (closed at RM56.00yesterday) is now trading at an adjusted PE of 20.5 times (based on the last 4 quarters' adjusted EPS of 273 sen). However, this adjusted EPS of 273 sen may not be the earning going forward. If the earning going forward is similar to QE30/6/2016, then full-year EPS would be 214 sen. Thus forward PER would be 26 times. Compare this with HEIM & Carlsbg's PER of 21 times & 19 times respectively, BAT appears more expensive.

In addition, BAT has paid out a quarterly dividend of 78 sen; thus giving a Dividend Yield of 5.6%. The dividend payment has declined in line with lower earning to 55 sen last quarter and 45 sen in the latest quarter. Assuming the dividend payment stabilized ta 45 sen a quarter, its DY would be 3.2%. Again, this compared less favorably to HEIM & Carlsbg's DY of 4.6% & 5.2% respectively.

Technical Outlook

BAT peaked at RM74 in 2014. Its steady decline over the past 2 years picked up momentum due to poor financial performance after the sharp rise in excise duties on cigarettes in 2015. The drop was so severe that the share price went thru the long-term uptrend line support at RM50-51.00 mark.


Chart 3: BAT's monthly chart as at July 26, 2016 (Source: ShareInvestor)

BAT has since rebounded but its upside is capped by the intermediate downtrend line at RM56.00.


Chart 4: BAT's weekly chart as at July 26, 2016 (Source: ShareInvestor)

Conclusion

Based on the poorer financial performance, unattractive valuation & bearish technical outlook, BAT is rated a SELL. If you want to be invested in beer & cigarette stocks, my preference is for Carlsbg.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, BAT.

Thursday, May 05, 2016

BAT: Bullish Reversal Achieved?

BAT has a candlestick pattern over the past 2 days that's very similar to a bullish engulfing pattern. The stock staged a fierce rebound yesterday after 4 days of sell-off which saw the stock shedding nearly RM14.00. However, BAT will immediately run into a resistance at RM47.70 from the gap down recorded on April 29. Can it surpass that level? If it failed to do so today, it may drift back down to RM45.00 for a short breather.

Based on bullish reversal, BAT could be a trading BUY.


Chart: BAT's daily cahrt as at May 4, 2016 9Source: Shareinvestor.com)
  
Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, BAT.

Wednesday, April 27, 2016

BAT: Paying The Price of High Duties

Result Update

For QE31/3/2016, BAT's net profit dropped by 24% q-o-q or 6% y-o-y to RM196 million while revenue dropped by 9% q-o-q or 12% y-o-y to RM1.06 billion. Revenue declined 19.9% (or RM253 million) and Gross Profit declined 21.9% (or RM99 million) due to 34.0% -reduction in sales volume following  the  November  2015  steep  excise  increase.  Despite a drop in Operating Expenses, driven mainly by timing of administrative expenses, the huge drop in sales meant that operating overhead was "under-recovered". This led to a drop in Profit from Operations and Profit before Tax of 28.2% (or RM92  million) and 28.8%  (or RM94  million) respectively.


Table: BAT's last 8 quarterly results


Chart 1: BAT's last 36 quarterly results

Putting 4Q2015 in perspective

The sharp drop in revenue which began in QE31/12/2015 continued. That is the result of the unexpectedly jump in excise duties (off-budget!!). I had earlier expected the domestic sales is expected to recover in the next few quarters but the opposite has happened. This is partly due to the easy availability of illegal cigarettes as well as the difficult time affecting Malaysians of all walks of life.

Due to this challenging operating environment, BAT has announced its plan to restructure its business, which I reproduce below:  

Restructuring of Business Operations: On 17th March 2016, the Group announced that it will be restructuring its business operations by sourcing tobacco products for its domestic market from other BAT factories regionally and would cease its manufacturing operations located at Virginia Park, Jalan University, 46200, Petaling Jaya, Selangor. The winding down of factory operations will be carried out in stages and targeted to complete by the 2nd half of 2017.


The restructuring is in line with the Group’s efforts towards realising a new and more sustainable business model, amidst an increasingly challenging business environment. The higher excise environment has ultimately led to the sharp rise in illegal cigarettes and significantly lower legal sales volumes resulting in rising cigarette production costs. The restructuring will enable the Group to sharpen its commercial capabilities whilst optimising the supply chain and transactional activities to ensure that the Group remains a competitive consumer-focused market leader.


The winding down of the factory operations will affect approximately 230 employees and they will be provided with a benefit package as well as the option to undergo a career-transition programme. The equipment and machinery currently used for factory operations is intended to be sold to related parties within BAT group of entities.


The land upon which the factory operations are located will be disposed of by the Group by way of a public tender exercise. An independent real estate agent has been appointed by the Group to act for and on behalf of the Group to deal with all matters relating to the proposed disposal of the land. The public tender exercise is scheduled to complete on or about May 2016. An announcement in relation to the proposed disposal of land will be made after the sale and purchase agreement for the land is signed. Shareholders’ approval on the disposal will be sought in accordance with the Main Market Listing Requirement of Bursa Malaysia Securities Berhad.

I have posted earlier that this restructuring plan should be positive for the stock in the long run. Until then, investors will have to live with lower earnings for the next few quarters.
 
Valuation

BAT (closed at RM54.50 yesterday) is now trading at a PE of 18.4 times (based on the last 4 quarters' EPS of 295 sen). BAT paid out a dividend of RM2.89 for the last 4 quarters; thus giving a Dividend Yield of 5.3%. At these PER & DY, BAT is deemed fairly attractive.

Technical Outlook

At the current price of RM54.50, BAT has broken below the support from its long-term uptrend line, SS at RM55.00. Unless this breakdown is reversed quickly, BAT may continue to slide to its next support from the psychological RM50.00 mark.


Chart 3: BAT's daily chart as at April 26, 2016 (Source: ShareInvestor)

Conclusion

Despite the poorer financial performance, BAT is still a good stock for long-term investment based on fair valuation. However its technical outlook has turned bearish, I would revise the rating from long-term BUY to HOLD.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, BAT.