Showing posts with label TUNEPRO. Show all posts

Thursday, September 07, 2017

Tunepro: A Possible Trading Buy

Results Update

For QE30/6/2017 (2Q17), Tunepro's net profit rose 9% q-o-q but dropped 51% y-o-y to RM13 million while revenue rose 3% q-o-q or 7% y-o-y to RM134 million. Revenue came from increase of RM3.2 million in Gross Earned Premium from the Philippines and Middle East markets in general reinsurance business and increase of RM0.6 million in investment income, mainly due to reversal of MMIP investment income in 1Q17. There was a decrease of RM2.0 million in Group's segment profit, from RM15.1 million in 1Q17 to RM13.1 million in 2Q17, due mainly to increases in net commissions mainly from general insurance business. [Note: Tunepro's result for QE30/9/2016 was released on August 18.]


Table: Tunepro's last 8 quarterly results


Graph: Tunepro's last 23 quarterly results

Valuation

Tunepro (closed at RM1.09 yesterday) is now trading at a PER of 14.7 times (based on last 4 quarters' EPS of 7.43 sen). Its dividend yield is about 4.6% (based on dividend payment of 5 sen in FY16). Based on these 2 valuation models, Tunepro is deemed fairly valued.

Technical Outlook

Tunepro broke below the medium-term downtrend line, rr at RM1.02 in late August. It then rallied to a high of RM1.12 before correcting back to about RM1.05. Today, it broke above the recent high of RM1.12- possibly starting its recovery.


Chart 1: Tunepro's daily chart as at Sep 7, 2017_12.30pm (Source: Malaysiastock.biz) 

Tunepro's immediate resistance could be the intermediate downtrend line, RR at RM1.30. If it can also break above this downtrend line, then Tunepro could begin its next upleg.


Chart 2: Tunepro's weekly chart as at Sep 7, 2017_12.30pm (Source: Malaysiastock.biz) 

Conclusion

Despite weaker financial performance and negative technical outlook, Tunepro remains a good stock for a recovery play due to its recent sharp selldown from RM1.60 to RM1.00.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Wednesday, December 14, 2016

Tunepro: Earning Dropped Sequentially

Results Update

For QE30/9/2016, Tunepro's net profit dropped by 46% q-o-q but rose 11% y-o-y to RM14 million while revenue rose less than 1% q-o-q or 4% y-o-y to RM126 million. Revenue rose by RM0.6 million q-o-q due to increase of RM3.1 million in GEP offset by decrease in investment income of RM2.5 million. PBT declined by RM18.5 million q-o-q due to a drop in pre-tax profits in general insurance of RM16.9 million; RM1.1 million in investment holding segment; and RM0.5 million in share of profits of associates. The drop in pre-tax profits in general insurance was in turn due to reduced share of results from Malaysian Motor Insurance Pool (MMIP) of RM15.6 million and increase in management expenses of RM1.3 million. [Note: Tunepro's result for QE30/9/2016 was released on November 25.]


Table: Tunepro's last 8 quarterly results


Graph 1: Tunepro's last 20 quarterly results

Tunepro's revenue continued to track the revenue of Airasia. Thus, its performance will continue to be healthy as Airasia expands its wings across Asia.


Graph 2: Tunepro & Airasia's last 20 quarterly revenue
 
Valuation

Tunepro (closed at RM1.37 yesterday) is now trading at a PER of 11.9 times (based on last 4 quarters' EPS of 11.56 sen). At this PER, Tunepro is deemed attractively valued.

Technical Outlook

Tunepro broke below the uptrend line, SS at RM1.60 about 4 weeks ago. Last Froday, it broke below the support from the horizontal line at RM1.45. Its next support will come from the hroizonatl line at RM1.20.


Chart: Tunepro's weekly chart as at Dec 13, 2016_3.30pm (Source: Chartnexus) 

Conclusion

Despite weaker financial performance and negative technical outlook, Tunepro remains a good stock for long-term investment.  

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Monday, August 22, 2016

Tunepro: Quarterly Earnings at a New High

Results Update

For QE30/6/2016, Tunepro's net profit rose by 17% q-o-q or 64% y-o-y to RM26.5 million while revenue was mixed- down 3% q-o-q but rose 9% y-o-y to RM126 million. Revenue dropped by RM4.0 million q-o-q due to decrease of RM6.9 million in GEP which was partially offset by increase in investment income of RM2.9 million. PBT increased by RM9.2 million q-o-q mainly due to an increase of RM12.8 million in pre-tax profits in general insurance, which was partially offset by decreases of RM2.1 million in pre-tax profits in general reinsurance and RM0.7 million in share of profits of associates in Thailand.


Table: Tunepro's last 8 quarterly results

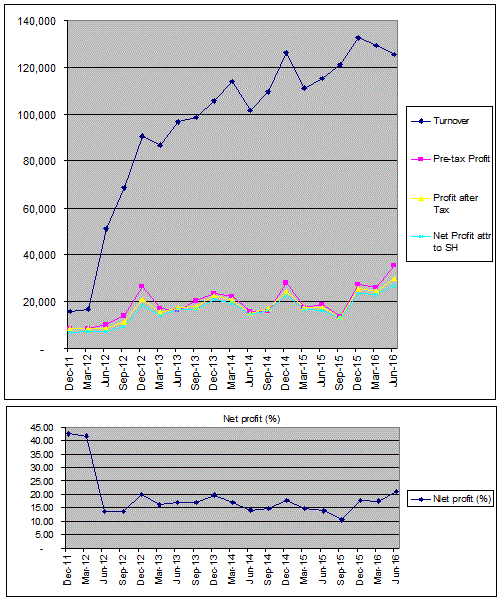
From the chart below, we can see that PBT was able to surpass the previous high of RM27 million convincingly. Is Tunepro's earnings due for takeoff?


Chart 1: Tunepro's last 19 quarterly results

Valuation

Tunepro (closed at RM1.64 last Friday) is now trading at a PER of 14.4 times (based on last 4 quarters' EPS of 11.36 sen). Tunepro's earning grew by 19.7% in the past 4 quarters- giving the stock a PEG ratio of 0.7 time. As the PEG ratio is less than 1 time, Tunepro is deemed attarctive.

Technical Outlook

Tunepro broke above its downtrend line, RR at RM1.25 in late February. Tunepro is now in an uptrend line, SS with support at RM1.50. Its immediate resistance is from its overhead horizontal line at RM1.80.


Chart 2: Tunepro's weekly chart as at Aug 19, 2016 (Source: ShareInvestor.com) 

Conclusion

Based on improved financial performance, reasonable valuation & bullish technical outlook, Tunepro remains a good stock for long-term investment. 

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision

Sunday, May 29, 2016

Tunepro: Earnings Rose y-o-y

Results Update

For QE31/3/2016, Tunepro's net profit rose by 37% q-o-q to RM23 million on the back of a 16%-increase in revenue to RM130 million. Compared to the preceding quarter, net profit dropped 4% while revenue dropped 2%. Revenue dropped q-o-q by RM3.1 million due to decrease of RM3.7 million in investment income of general insurance, offset by increase of RM0.6 million in gross earned premium. PBT dropped mainly due to increase in marketing costs in relation to digital marketing campaign in line with the Group's vision on being a leading digital insurer and unrealized foreign exchange loss.


Table: Tunepro's last 8 quarterly results

While profits in the last quarter are weaker than the preceding quarter, the drop was minimal when compared to previous years. This - coupled with higher dividend (a reflection of management's confidence) - seems to suggest that the company could be on a growth path.


Chart 1: Tunepro's last 18 quarterly results

Valuation

Tunepro (closed at RM1.51 last Friday) is now trading at a PER of 15 times (based on last 4 quarters' EPS of 10.0 sen). At this PER, Tunepro is deemed fairly valued.

Technical Outlook

Tunepro broke above its downtrend line, RR at RM1.25 in late February. Tunepro has just surpassed the strong resistance from the horizontal line at RM1.50. With MACD above the zero line, uptrend will commence soon. The only thing lacking is the ADX is still below the 20-mark.


Chart 2: Tunepro's weekly chart as at May 27, 2016(Source: ShareInvestor.com) 

Conclusion

Based on improved financial performance, reasonable valuation & bullish technical outlook, Tunepro is a good stock for long-term investment. 

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Tunepro.

Wednesday, May 11, 2016

Tunepro: Playing Catch-up

Results Update

For QE31/12/2015, Tunepro's net profit rose by 83% q-o-q or 4% y-o-y to RM24 million while revenue increased by 10% q-o-q or 5% y-o-y to RM133 million. Revenue increased q-o-q by RM11.6 million due to increase of RM7.1 million in gross earned premiums ("GEP") and RM4.5 million increase in investment income. Segmental profit increased by RM13.9 million q-o-q  due to a RM9.2 million in pre-tax profits in general insurance segment and RM3.6 million increase in general reinsurance segment

(Note: This quarterly result was announced on Feb 23. The next quarterly result was probably be announced next week.)


Table: Tunepro's last 8 quarterly results


Chart 1: Tunepro's last 16 quarterly results

Valuation

Tunepro (closed at RM1.48 as at 4:15pm today) is now trading at a PER of 16 times (based on last 4 quarters' EPS of 9.2 sen). At this PER, Tunepro is deemed fairly valued.

Technical Outlook

Tunepro broke above its downtrend line, RR at RM1.25 in late February. Since then, it has been trapped in a "flag formation" with resistance at RM1.48-1.50 and support at RM1.29-1.31. An upside breakout of this pattern - the resistance from the horizontal line at RM1.50 -  could signal the start of its uptrend. When the breakout happens, Tunepro will finally catch up with its "siblings"-- Airasia and AAX. Until then, the good level to buy into this stock is around RM1.30-1.35.


Chart 2: Tunepro's weekly chart as at Oct 5, 2015 (Source: ShareInvestor.com) 

Conclusion

Based on improved financial performance, reasonable valuation & mildly bullish technical outlook, Tuneins is a good stock for long-term investment. An upside breakout above RM1.50 could be the start of better days ahead for this stock.

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Tunepro.