Showing posts with label MYEG. Show all posts

Monday, October 22, 2018

MYEG: MACC's Highly Unusual Comment

Last Saturday, MYEG announced that it has received a letter from MACC which has purportedly confirmed that MYEG and its directors are not under investigation, nor a party to the investigation leading to charges against Zahid. The announcement on Bursa's website is here.

In addition, I have also looked at 3 sources- The Star, The Edge and FMT and in all of these reports, the party announcing that news was MYEG. There was no letter offered to support this announcement. Meanwhile MACC was completely silenced on this "confirmation or clarification" supposedly given to MYEG. Was MACC approached by The Star or The Edge about the issuance of this letter of confirmation/clarification? That was also absent. This is my take:

I have serious doubt about that comment. As reported, Zahid received money from X in return for helping X secured a contract/project from MYEG. Let’s breakdown the alleged offence in 2 parts. The 1st part is Zahid received money and X received contract/project from MYEG. The 2nd part is Zahid received a favor from MYEG and MYEG obtained/repaid an IOU from/to Zahid.

The amount involved and number of such “transactions” is significant; a total of 24 cheques worth over RM13 million between July 15, 2016 and Feb 8, 2017 were received by Zahid and the party(ies) that made the payments, subsequently secured contracts from MYEG.


If MACC chose not to investigate these offences, it will be in dereliction of its duties. Thus, I don’t put much weight on MYEG’s announcement that MACC has somehow “cleared” the company of any wrongdoing relating to the above alleged offence.

****

Chartwise, MYEG (RM1.38 as at 10.26am) has support at the horizontal line at RM1.33-1.35 or the intermediate uptrend line at RM1.05. The immediate resistance is at the horizontal line at RM1.40 or the short-term downtrend line at RM1.50.

Based on the above, I would recommend a SELL on MYEG at the current price.


Chart: MYEG's daily chart as at Oct 19, 2018 (Source: Malaysiastock.biz)

Friday, October 19, 2018

Zahid Hit with 45 Charges (UPDATED)

Today, our former Deputy Prime Minister, Ahmad Zahid Hamidi was charged in courts for committing 45 offenses, listed below:


For more, go here.

Of interest to us in the stock market are the following charges for receiving gratification:


My take is that the above charges could lead to legal liabilities for Datasonic Group Bhd ("DSONIC") if it can be proven that it offered money to induce the award of the contract by the Minister. In the case of MYEG, it may still be held liable if it were a party to an illegal act. If a company is found guilty of committing an offense, the company may be fined and/or the contract awarded may be terminated. Thus, I can see that implication of these gratification charges may have great impact on DSONIC than on MYEG. Nevertheless, since both companies are dependent on government's contracts in the long run, any blemish on its business conduct will impact its chance of success to secure new contracts or renewal of existing contracts.

*****

Chartwise, DSONIC has broken below the line connecting its recent lows, AB. 


Chart 1: DSONIC's weekly chart as at 19, Oct 2018_12.30 (Source: Malaysiastock.biz)

MYEG is now resting on its intermediate uptrend line at RM1.13. Its next support levels are at RM1.10, RM1.00 & RM0.95.


Chart 2: MYEG's weekly chart as at 19, Oct 2018_12.30 (Source: Malaysiastock.biz)

DSONIC has denied that it had issued any payment to the former DPM (here) while MYEG has requested a suspension of the trading of the shares on the exchange.

In view of the poor market sentiment, the negative news on DSONIC and MYEG will have longer negative implication. If you want to get into these stocks, you have to accept that the potential reward comes with high risk.

(Note: I have attempted to re-present this post with updated information as well as to tidy up the presentation. Alas, the presentation is still less than satisfactory.)

Monday, March 06, 2017

MYEG: Earnings Continues To Rise

Results Update

In QE31/12/2016, MYEG's net profit rose 18% q-o-q or 57% y-o-y to RM48 million while revenue rose 13% q-o-q or 40% y-o-y to RM89 million. The increase in Revenue and PAT is primarily attributable to an increase in revenue contribution from foreign worker rehiring program services as well as from motor vehicle trading related services. However, the increase in Revenue was offset by higher marketing expenses and personnel related expenses. [Note: Myeg's result for QE31/12/2016 was released Feb 27, 2017.]


Table: MYEG's last 8 quarters' P&L


Graph: MYEG's last 17 quarters' P&L

"New" Development

Last Friday, MyEG confirmed that the value of the five-year concession awarded by the Government to provide online renewal of temporary employment passes for foreign workers (from May 23, 2015 to May 22, 2020) is RM553.85mil (here). This concession is expected to contribute positively to the earnings and net assets per share for the financial years ending June 30, 2017 onwards until the expiry of the project. This concession was already made public in January (here).
 

Valuation

MYEG (closed at RM1.77 last Friday) is now trading at a trailing PER of 37x (based on last 4 quarters' EPS of 4.8 sen). Based on average earning CAGR of 70% over the past 2 years, PEG ratio is comfortably below 1- which means that MYEG valuation is deemed "attractive" for a growth stock.

Technical Outlook

MYEG has been in a steady uptrend after it broke above the resistance from the horizontal line at RM0.15 in 2013.


Chart 1: MYEG's monthly chart as at Mar 3, 2017 (Source: ShareInvestor)

Last week, MYEG broke above the line connecting the peaks for the past 15 months (AB) at RM1.73-1.75. With this upside breakout, MYEG may continue its prior uptrend.


Chart 2: MYEG's weekly chart as at Mar 3, 2017 (Source: ShareInvestor)
Conclusion

Based on good financial performance, attractive valuation (supported by rapid growth) and positive technical outlook, MYEG could be a good stock for long-term investment. Good entry level is at RM1.75.

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Monday, September 05, 2016

MYEG: Earnings Jumped

Results Update

In QE30/6/2016, MYEG's net profit rose 54% q-o-q or 122% y-o-y to RM51 million while revenue rose 24% q-o-q or 94% y-o-y to RM87 million. The increase in revenue and PAT was primarily attributable to an increase in revenue contribution from FWP and foreign worker rehiring program services; and contribution from our newly acquired subsidiary, Cardbiz Holding Sdn Bhd and its group of companies


Table: MYEG's last 8 quarters' P&L


Chart 1: MYEG's last 14 quarters' P&L

Valuation

MYEG (closed at RM2.18 last Friday) is now trading at a trailing PER of 36x (based on last 4 quarters' EPS of 5.95 sen). Based on average earning CAGR of 65% over the past 2 years, PEG ratio is comfortably below 1- which means that MYEG valuation is deemed 'attractive" for a growth stock.

Technical Outlook

MYEG has been in a steady uptrend after it broke above the resistance from the horizontal line at RM0.22.


Chart 2: MYEG's monthly chart as at Sep 2, 2016 (Source: ShareInvestor)

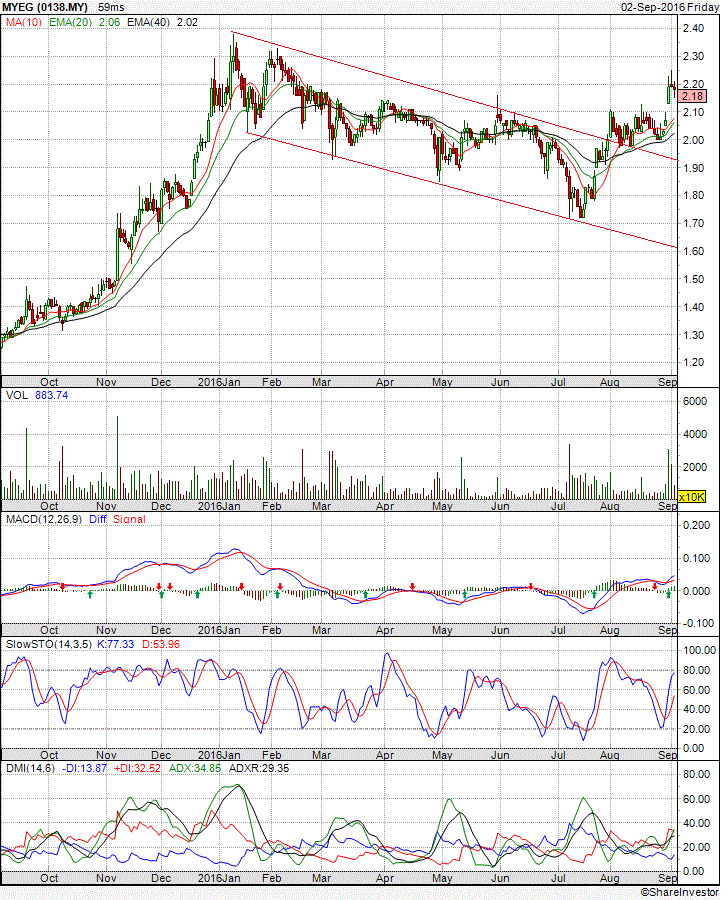
Since MYEG made a high of RM2.40 in early January this year, it has been sliding down in a channel. It made a low of RM1.70 in July and then rebounded strongly. In August, It broke above the downward channel at RM2.00. The stock could retest the January high of RM2.40 in the current rally.


Chart 3: MYEG's weekly chart as at Sep 2, 2016 (Source: ShareInvestor)

Conclusion

Based on good financial performance & condition, "attractive" valuation (supported by rapid growth) and positive technical outlook, MYEG could be a good stock for long-term investment. Good entry level is at RM2.10.

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Monday, July 11, 2016

MYEG: Testing Strong Support

MYEG was fined RM2.272 million in June by the Malaysian Competition Commission for abusing its dominant position in the online foreign workers permit ('PLKS') renewals processing when its its wholly-owned subsidiary, My E.G. Commerce Sdn Bhd (MyEG Commerce) participates as an insurance agent in the PLKS applications. The participation of MyEG Commerce has caused competitors offering insurance coverage to be at a disadvantage. MYEG has been given 60 days to rectify the situation, failing which a higher daily fine will be levied against it.

From the chart below, we can see that MYEG peaked in early January at about RM2.30. After that, it has dropping in a downward channel, R-R, R1-R1). Today the share price touched the lower line, R1-R1 at RM1.72. This is also the accelerated uptrend line S1-S1 support as well as the horizontal line. Thus I believe the stock is likely to enjoy a technical rebound from here. We will have to wait for a while to see whether the low today the end of the current downtrend or merely a temporary bottom.

From the recent post, we can compute MYEG's trailing PER at 37x (based on current price of RM1.78 & EPS of 4.8 sen). MYEG's earning has a CAGR of 60%; giving it a PEG ratio of 0.6x. Thus, MYEG is deemed attractive as a growth stock as its PEG ratio is less than 1x.

Based on this valuation, MYEG could be a decent stock to consider for your investment at the current price of below RM1.80. You are advised to exercise careful discretion if you choose to trade this stock.


Chart: MYEG's weekly chart as at July 11, 2016_3.15pm (Source: Kenanga/Chartnexus)

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, MYEG.

Tuesday, May 31, 2016

MYEG: A Steady Growth Stock

Background

My E.G. Services Bhd ('MYEG') provides E-Services between the Government and the people and businesses. Its services include electronic delivery of driver and vehicle registrations, licensing and summons services and utility bill payments. In the past 5-6 quarters, its new business - online renewal of foreign worker permits - has grown into a major business, contributing a sharp rise in its revenue & profits.

other businesses like the replacement of MyKad (the chip-based national identity card), paying Road Transport and police summonses, auto insurance, and road tax renewal, - See more at: http://www.themalaymailonline.com/tech-gadgets/article/facing-backlash-myeg-defends-deal-with-malaysian-government#sthash.OAhaHM9X.dpu
Recent Financial Performance

Over the past 5 quarters, MYEG's top-line and bottom-line have risen steadily. Earnings grew at a 85% in the last 4 quarters!


Table: MYEG's last 14 quarters' P&L


Chart 1: MYEG's last 14 quarters' P&L

Financial Position

MYEG's financial position as at 31/3/2016 is deemed healthy with current ratio at 2.2x and total liability to equity at 0.6x.

Valuation

MYEG (closed at RM2.05 yesterday) is now trading at a trailing PER of 42x (based on last 4 quarters' EPS of 4.8 sen). Based on CAGR of 60% over the past 2 years, PEG ratio is still below 1. Thus MYEG valuation is deemed 'reasonable' for a growth stock.

Technical Outlook

MYEG has been in a steady uptrend since it broke above the resistance from the horizontal line at RM0.23-0.24.


Chart 2: MYEG's monthly chart as at May 30, 2016 (Source: ShareInvestor)

During this uptrend, MYEG had 3 prolonged consolidation phases. The first was Jan-Aug 2014 & the second one was Mar-Oct 2015. It is currently in the 3rd consolidation phase. The 2nd consolidation phase was supported by the 40-week EMA line. If the same applies to the current consolidation, we can expect the share price to be supported at RM1.90-2.00. Continuation of the long-term uptrend will begin if the share price surpasses the recent high of RM2.30-2.35.


Chart 3: MYEG's weekly chart as at May 30, 2016 (Source: ShareInvestor)

Conclusion

Based on good financial performance & condition, "reasonable" valuation (supported by rapid growth) and positive technical outlook, MYEG could be a good stock for long-term investment. Good entry is at RM1.90-2.00.

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, MYEG.