Showing posts with label industrial products and services. Show all posts

Tuesday, February 22, 2022

CSCSTEL: Earnings Soared On Higher Selling Prices

Results Update

For QE31/12/2021, CSCStel's net profit rose 290% q-o-q or 81% y-o-y to RM39 million while revenue rose 164% q-o-q or 45% y-o-y to RM532 million. The higher revenue was mainly due to significant increase in steel price, while the sales volume has reduced by 16.5% compared to preceding year’s corresponding quarter. Despite the decrease in sales volume, the Group reported a higher profit before tax of RM51 million in the current quarter, an increase of 77% compared with a profit before tax of RM29 million a year ago.


Table: CSCStel's last 8 quarterly results


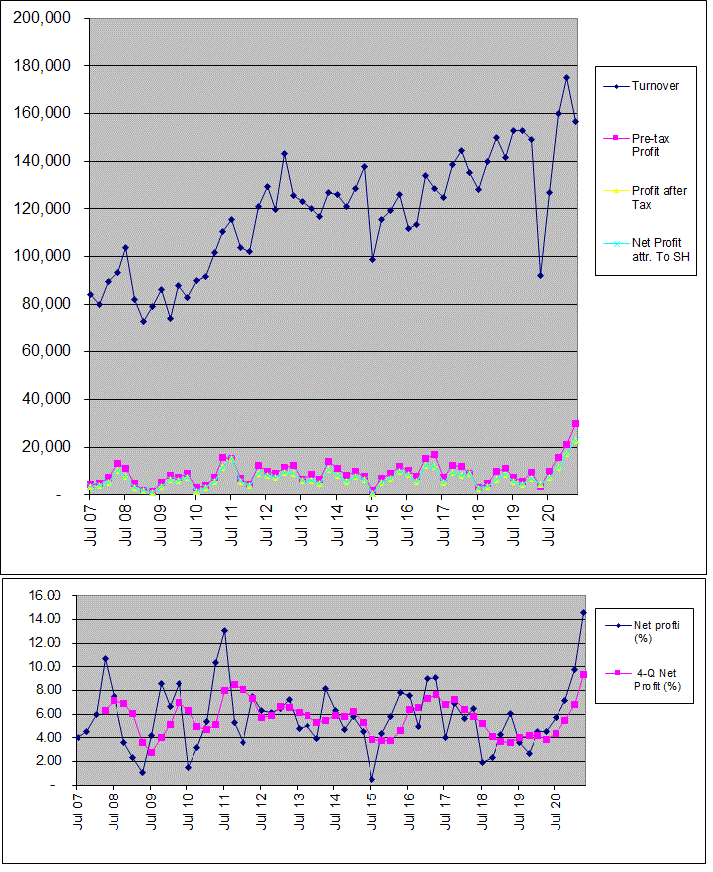
Graph: CSCStel's P&L for last 57 quarterly results

Financial Position

As at 31/12/2021, CSCStel's financial position is deemed very healthy with current ratio at 6.2 times and gearing ratio at 0.18 time. It has net cash of RM162 million which is equivalent to RM0.44 per share.

Valuation

CSCStel (RM1.37 yesterday) has a PER of 5.9 times (based the last 4 quarters' EPS of 23.3 sen). If the cash balance of RM0.44 per share is deducted from the share price, CSCStel's PER would be reduced further to only 4 times. At this PER multiple, CSCStel is deemed very attractive. In addition, CSCStel has proposed a dividend of 14 sen for the current year- an increase of 100% over last year's dividend. At this dividend payout, CSCSTEL's dividend yield stands at 10.2%.

Technical Outlook

CSCStel has been trading in a wavy pattern. The share price appears poised to begin its next wave upwards.


Chart: CSCStel's monthly chart as at Feb 21, 2022(Source: isaham.my)

Conclusion

Based improved financial performance, healthy financial position and attractive valuation, CSCStel is a good stock for long-term investment.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Monday, February 21, 2022

MSC: Earnings Soared As Tin Prices Made New Historical High

Results Update

For QE31/12/2021, MSC's net profit rose 121% q-o-q or 329% y-o-y to RM64 million while revenue rose 16.7% q-o-q or 9.7% y-o-y to RM255 million.

Revenue rose y-o-y due to higher tin price has negated the drop in refined tin production quantity as a result of continued operation disruption from the declaration of force majeure because of coronavirus-related disruption to production. The force majeure, which has been in force since 7 June 2021 (here), had been lifted on 20th December 2021 (here).

The Group recorded a profit before tax of RM85.2 million in 4Q 2021 as compared with RM20.5 million in 4Q 2020, mainly due to higher average tin prices of RM158,267 (4Q 2021) as compared with RM76,870 (4Q 2020) per metric tonne. 

The tin smelting segment recorded a profit before tax of RM13.9 million in 4Q 2021 as compared with RM17.8 million in 4Q 2020, mainly due to the absence of a reversal of inventories written down of RM21.1 million that was recorded in 4Q 2020. The tin smelting segment has also benefited from higher profit margins from sales of refined tin derived from its tin intermediates, and also from higher average tin prices. 

The tin mining segment recorded a profit before tax of RM57.9 million in 4Q 2021 as compared with RM11.4 million in 4Q 2020, mainly due to higher average tin prices in 4Q 2021. 

The Group’s share of results of associates and joint ventures recorded a net share of profit of RM1.0 million in 4Q 2021 as compared with a net share of loss of RM4.1 million in 4Q 2020.


Table: MSC's last 8 quarterly results


Graph; MSC's last 60 quarterly results

Tin Price Movement

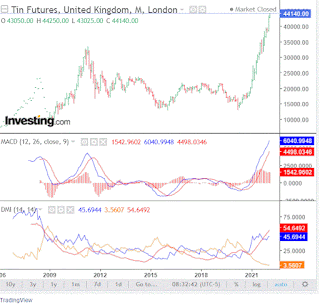
Like prices of many commodity, tin prices rose sharply after the start of the pandemic, from a low of USD13,350 in March 2020 to the current price of USD44,200. The sharp price rally is driven by increased demand for tin used in the production of electronics and electrical products coupled with constrained supply due to the COVID-19 pandemic. Any change in this supply & demand dynamics will have an impact on the prices of tin. 


Chart 1: Tin price chart as at 18 Feb 2022 (Source: Investing.com)

Valuation

MSC (closed at RM4.08 last Friday) is trading at a PE of 14 times (based on the last 4 quarters' EPS of 28.50 sen). As such, MSC is deemed fairly valued.

Technical Analysis

MSC rose sharply after it broke above the line connecting its peaks from 2011 to 2020 (R1-R1) at RM1.00 in December 2020 (see Chart 2). This bullish breakout sent the share price to a high of RM2.93 in February 2021. Thereafter, the share prices consolidated until October 2021 under the downtrend line, RR (see Chart 3). In middle of October 2021, MSC broke above the downtrend line, RR at RM2.50 and the uptrend resumes.

Chart 2: MSC's monthly chart as at Feb 18, 2022 (Source: isaham.my)


Chart 3: MSC's daily chart as at Feb 18, 2022 (Source: isaham.my)

Conclusion

Based on good financial performance, fair valuation & bullish technical outlook, MSC could be a good stock to ride the rally in tin prices. 

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Wednesday, December 29, 2021

SCGM: Earnings Continued To Stall

 Results Update

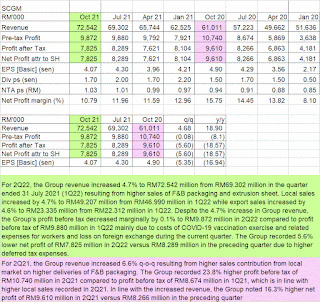
In QE31/10/2021 (2Q22), SCGM's net profit dropped 6% q-o-q or 19% y-o-y to RM7.8 million while revenue increased 5% q-o-q or 19% y-o-y to RM72.5 million. 

For 2Q22, the Group revenue increased 5% q-o-q "resulting from higher sales of F&B packaging and extrusion sheet. Local sales increased by 4.7% to RM49.207 million from RM46.990 million in 1Q22 while export sales increased by 4.6% to RM23.335 million from RM22.312 million in 1Q22. Despite the 4.7% increase in Group revenue, the Group’s profit before tax decreased marginally by 0.1% to RM9.872 million in 2Q22 compared to profit before tax of RM9.880 million in 1Q22 mainly due to costs of COVID-19 vaccination exercise and related expenses for workers and loss on foreign exchange during the current quarter. The Group recorded 5.6% lower net profit of RM7.825 million in 2Q22 versus RM8.289 million in the preceding quarter due to higher deferred tax expenses".

 
Table: SCGM's last 8 quarterly results

 
Graph: SCGM's last 51 quarterly results

Financial Position

SCGM's financial position is deemed healthy with current ratio at 1.65 times while gearing ratio is elevated at 0.55 time.

Valuation

SCGM (closed at RM2.42 yesterday) is now trading at a PE of 15X (based on the last 4 quarters' EPS of 16.54sen).  At this PE, SCGM is deemed fairly attractive.

Technical Outlook

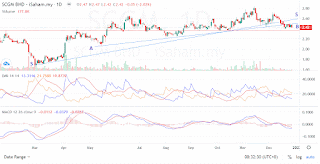
SCGM's medium-term uptrend may have ended after the share prices went below the uptrend line, SS. Its next support should be at the horizontal line at RM2.35.


Chart 1: SCGM's daily chart as at  Dec 28, 2021 (Source: iSaham.my)


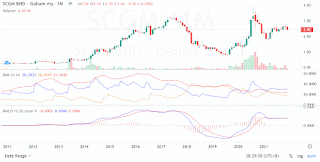
Chart 2: SCGM's monthly chart as at  Dec 28, 2021 (Source: iSaham.my)

Conclusion

Despite the weaker financial performance, SCGM is still a good stock for long-term investment based on healthy financial position & fair valuation,

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Wednesday, June 30, 2021

HIAPTEK: Earnings Remained Strong

Results Update

For QE30/4/2021, Hiaptek's net profit rose 117% q-o-q or 12-fold to RM66 million while revenue was mixed- down 7% q-o-q but up 100% y-o-y to RM330 million. Its revenue decreased by 7% q-o-q due to lower sales volume for both the Trading and Manufacturing divisions attributable to the Chinese New Year holidays in February 2021. Despite the lower revenue, Profit from Operations increased by 67% to RM63.53 million due to higher steel prices and cost optimization efforts undertaken during the quarter under review. "Together with an improved contribution from the JV entity of RM19.81 million in the current quarter as compared to RM2.88 million in the immediate preceding quarter, the Group recorded a 114% improvement in Profit before Tax to RM80.16 million in 3Q2021 as compared to RM37.42 million in 2Q2021". 

The company is positive on its outlook, post lockdown, given the strength of steel prices and the JV entity’s continuous investments in plant and equipment to achieve cost efficiencies. The JV entity’s first 200,000 tonnes of coke oven plant is expected to complete by the second half of 2021, in which substantial cost savings can be achieved. For more, go here.


Table: Hiaptek's last 8 quarterly results


Graph: Hiaptek's last 70 quarterly results

Financial Position

Hiaptek's financial position as at 30/4/2021 is deemed satisfactory with current ratio at 1.63 times and gearing ratio at 0.49 time. 

Valuation

Hiaptek (closed at RM0.565 yesterday) is now trading at a PE of 6.8 times (based on last 4 quarters' EPS of 8.29 sen). At this PE ratio, Hiaptek is deemed fairly attractive.

Technical Outlook

Hiaptek has broken above its long0term downtrend line at RM0.20 in September 2020.

 
Chart 1: Hiaptek's monthly chart as at Jun 29, 2021 (Source: Kenanga BTX)

Hiaptek then rallied to a high of RM0.70 in May 2021. Like other steel stocks, Hiaptek has corrected substantially in the past few weeks. However it is still in an uptrend line with support at RM0.52. 


Chart 2: Hiaptek's weekly chart as at Jun 29, 2021 (Source: Kenanga BTX)

Conclusion

Based on improved financial performance & financial position, reasonable valuation and mildly bullish technical outlook, Hiaptek is a good stock for medium-term investment.

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Tuesday, June 29, 2021

SCGM: Steady Earnings Growth Continued

Results Update

In QE30/4/2021(4Q21), SCGM's net profit dropped 6% q-o-q or rose 11% y-o-y to RM7.6 million while revenue increased 5% q-o-q or 32% y-o-y to RM66 million. 

The Group Revenue increased q-o-q resulting from 13%-increase in local sales to RM46.106 million from RM40.757 million (due to higher deliveries of F&B packaging due to higher demand in general) which offset the 9.8% decline in export sales to RM19.638 million from RM21.768 million (due to lower sales of F&B packaging, in line with the past trend in which export sales would be higher during the few months prior to Christmas and New Year). 

The Group recorded a 24% higher profit before tax of RM9.792 million, which is in line with higher local sales recorded in 4Q21. Despite the increase in revenue, the Group recorded 6% lower net profit of RM7.621 million due to higher income tax expense and deferred tax expense.

 
Table: SCGM's last 8 quarterly results

 
Graph: SCGM's last 49 quarterly results

Financial Position

SCGM's financial position is deemed healthy with current ratio at 1.55 times while gearing ratio is elevated at 0.62 time.

Valuation

SCGM (closed at RM2.45 yesterday) is now trading at a PE of 14 X (based on the last 4 quarters' EPS of 17.36 sen).  At this PE, SCGM is deemed fairly attractive.

Technical Outlook

SCGM has been on a steady rise, from the low of RM1.69 recorded in March this year. It is rising on an uptrend line, with support at RM2.30.


Chart 1: SCGM's daily chart as at Jun 28, 2021 (Source: Kenanga BTX)

Prior to this, it had a big drop from its all-time high of RM3.95 in August 2020. 


Chart 2: SCGM's weekly chart as at  Jun 28, 2021 (Source: Kenanga BTX)

Conclusion

Based on improved financial performance, healthy financial position & fairly attractive valuation, SCGM is a good stock for long-term investment. 

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.
Sunday, June 27, 2021

ASTINO: Good Earnings in a Weak Market

Result Update

In QE30/4/2021, Astino's net profit rose 22% q-o-q or 447% y-o-y to RM22.8 million while its revenue dropped 11% q-o-q but rose 70% y-o-y to RM156 million. Revenue has decreased q-o-q primarily due to decrease in local market demand. Profit before taxation increased by RM8.9 million to RM29.8 million, due to higher selling prices and improved operating cost. In addition, the allowance for diminution in value of inventories was RM2.3 million lower than the immediate preceding quarter. (Note: Astino is essentially a building material producer. For more, go here).


Table: Astino's last 8 quarters' results


Graph: Astino's last 52 quarters' results

Financial Position

Astino's financial position as at 30/4/2021 is deemed healthy with current ratio at 5.56x and gearing ratio at 0.15x.

Valuation

Astino (closed at RM1.40 last Friday) is now trading at a trailing PER of 6.4x (based on last 4 quarters' EPS of 21.74 sen). At this PER, Astino is deemed fairly attractive.

Technical Outlook

Astino has rallied strongly off its March 2020 low of RM0.37 ti make a high of RM1.70 in May 2021.


Chart 1: Astino's weekly chart as at Jun 25, 2021 (Source: Malaysiastock.biz)

From the monthly chart, we can see that Astino  has been moving within a large expanding triangle since 2014. Until it can break above the upper line at RM1.60, Astino is likely to move within the triangle. Since it has just tested the upper line, the more likely move is downward notwithstanding the good financial results achieved.


Chart 2: Astino's monthly chart as at Jun 25, 2021  (Source: Kenanga's BTX)

Conclusion

Based on good financial performance & financial position and fairly attractive valuation, Astino is a good stock for long-term investment. The near-term upside potential is limited as the share price will face strong resistance from the upper line of the expanding triangle.  

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Friday, April 30, 2021

LCTITAN: Earnings Soared

Background

Lotte Chemical Titan Holdings Bhd ("LCTitan") is a petrochemical producer. Its main products are polyolefins and olefins.Polyolefin products accounts for 18% & 9% of revenue & segmental results respectively while olefins & derivative products accounts for 82% & 91% of revenue & segmental results respectively.

Financial Performance

For QE31/3/2021, LCTitan's net profit rose 191% q-o-q to RM440 million on the back of a 23%-increase in revenue to RM2.367 billion. As compared to the results in the corresponding quarter last year, LCTitan has returned to the black due to increased sales volume & selling price. This, combined with higher plant utilization of 88%, helped to results of the group.


 Table: LCTitan's last 8 quarterly results

Looking at the graph below, we can see that LCTitan's profit has exceeded the high achieved in QE30/6/2016.

Graph: LCTitan's last 21 quarterly results

Financial Position

As at 31/3/2021, LCTitan's financial position is deemed healthy with current ratio at 7.03 times while gearing ratio was at only 0.14 time. 

Valuation

LCTitan (closed at RM2.99 last Wednesday) is now trading at a PE of 9 times (based on last 4 quarters' EPS of 33 sen). Based on this, LCTitan is deemed to be an attractive investment.

Technical Outlook

Looking at the weekly chart below, we can see that LCTitan broke above its downtrend line (in red) at RM1.80 in May 2020. Its uptrend since then has been capped just below RM3.00 (to be more precise at RM2.95). Last Wednesday's results announcement boosted the share price passed the resistance of RM2.95-3.00. This may mark the continuation of the uptrend in LCTitan's share price.


Chart: LCTitan's weekly chart as at April 28, 2021 (Source: Malaysiastock.biz)

Conclusion


Based on the good financial performance & position, attractive valuation & positive technical outlook, LCTitan is a good stock for long-term investment.

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Monday, December 21, 2020

SCGM: Earnings Continue to Rise

Results Update

In QE31/10/2020 (2Q21), SCGM's net profit rose 16% q-o-q or 138% y-o-y to RM9.6 million while revenue increased 7% q-o-q or 14% y-o-y to RM61 million. The group revenue increased 7% q-o-q resulting from higher sales contribution from local market on higher deliveries of F&B packaging. The Group recorded 24% higher profit before tax of RM10.7 million in 2Q21 compared to profit before tax of RM8.7 million in 1Q21, which is in line with higher local sales recorded in 2Q21. In line with the increased revenue, the Group noted 16% higher net profit of RM9.6 million in 2Q21 versus RM8.3 million in the preceding quarter

 
Table: SCGM's last 8 quarterly results

 
Graph: SCGM's last 47 quarterly results

Financial Position

SCGM's financial position is deemed healthy with current ratio at 1.49 times while gearing ratio is elevated at 0.67 time.

Valuation

SCGM (closed at RM2.48 yesterday) is now trading at a PE of 16.6X (based on the last 4 quarters' EPS of 14.92 sen).  At this PE, SCGM is deemed fairly attractive.

Technical Outlook

SCGM peaked at RM3.95 in early August. It has dropped back to around the RM2.50 level in the past few days. Its 200-day SMA line support is not far away at RM2.32.


Chart 1: SCGM's daily chart as at Dec 21, 2020 (Source: Malaysiastock.biz)


Chart 2: SCGM's weekly chart as at Dec 21, 2020 (Source: Malaysiastock.biz)

Conclusion

Based on improved financial performance, healthy financial position & fairly attractive valuation, SCGM is a good stock for long-term investment. The current price downtrend is likely to continue until a reversal is achieved, which may come once the share prices have surpassed the RM3.00 mark.

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.
Tuesday, August 11, 2020

BPPLAS: Earnings Rose Sharply

Result Update

For QE30/6/2020, BPPLAS's net profit rose 36% q-o-q or 87% y-o-y to RM8.5 million while revenue was mixed- up 3.5% q-o-q but down 7.4% y-o-y to RM80.3 million. 

Operating revenue rose q-o-q due to improved sales demand in 2Q20. A subsidiary of the Group received approval since the beginning of Movement Control Order (MCO), thus able to operate to deliver stronger sales performance because food packaging film, stretch film and customised film products produced by the Group are part of the critically required packaging for Food and other Essential Goods.

The Group recorded a historical high for the unaudited PBT and PAT for the quarter under review of RM11.3 million and RM8.5 million respectively, representing an increase of 36% and 36% compared to unaudited PBT and PAT of RM8.3 million and RM6.2 million respectively in 1Q20. The increase in the unaudited PBT and PAT for the quarter under review were mainly due to better product mix and production efficiencies.

Table: BPPLAS's last 8 quarterly P&L

Graph: BPPLAS's last 26 quarters' P&L

Financial Position

As at 30/6/2020, BPPLAS's financial position is deemed healthy with current ratio and gearing ratio at 4.6 times and 0.2 times. Cash in hand amounted to RM78.8 million or RM0.42 per share.

Valuation

BPPLAS (closed at RM1.40 yesterday) is now trading at a PER of 10 times (based on last 4 quarters' EPS of 14.36 sen). If the cash in hand is deducted from the share price, then BPPLAS's PER will be lowered to 7 times. BPPAS also paid a decent dividend totaling 8 sen last 4 quarters- giving it a dividend yield of 5.7%. Overall, BPPLAS is deemed fairly attractive.

Technical Analysis

BPPLAS has broken above the Downtrend line, RR at RM1.00 in early May. Its immediate support is at the horizontal line at RM1.35 while immediate resistance is at the horizontal line at RM1.60.

Chart: BPPLAS's mweekly chart as at Aug 11, 2020 (Source: Malaysiastock.biz)  

Conclusion

Based on good financial performance & position, attractive valuation and bullish technical outlook, BPPLAS could be a good stock for long-term investment. 

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.
Tuesday, December 17, 2019

Scientx: Earnings Dipped Sequentially

Result Update

For QE31/10/2019, Scientx's net profit rose 51% y-o-y to RM81 million on the back of a 23%-increase in revenue to RM877 million. When compared to the immediate preceding quarter, QE31/7/2019, net profit dropped 39% while revenue was down 7%.  The q-o-q decrease in revenue was mainly due to lower progress billings recognized for the property division. In line with the lower revenue recognized in current financial quarter, profit before taxation for the current financial quarter was RM116 million compared to the preceding financial quarter of RM177 million.


Table: Scientex's last 8 quarterly results


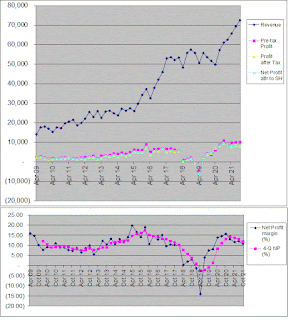
Graph: Scientex's last 57 quarterly results

Financial Position

As at 31/10/2019, Scientex's financial position is deemed satisfactory with current ratio at 1.2 times and gearing ratio at 0.7 time.

Valuation

Scientex (closed at RM9.53 today) is now trading at a trailing PE of 13.4 times (based on last 4 quarters' EPS of 70.99 sen). At this PER, Scientex is deemed fairly attractive.

Technical Outlook

Scientx is in an uptrend which has been capped by the horizontal line at RM9.40-9.50. If Scientx cannot charge above this resistance, its uptrend will continue.


Chart: Scientex's monthly chart as at Dec 17, 2019 (Source: Malaysiastock.biz)

Conclusion

Based on good financial performance, strong financial position, fairly attractive valuation and positive technical outlook, Scientex remains a good stock for medium to long-term investment.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.
Tuesday, December 10, 2019

SCGM: Earnings Increased Sharply

Results Update

In QE31/10/2019, SCGM's net profit rose 83% q-o-q or 144% y-o-y to RM4.0 million while revenue declined 4% q-o-q or 7% y-o-y to RM54 million. The q-o-q decline in revenue was attributed to lower sales contribution from non-customized F&B packaging i.e. lunch boxes, cups and plates. The Group recorded a profit before tax of RM4.2 million in 2Q20, compared to profit before tax of RM2.2 million in 1Q20, in line with lower raw material prices, lower interest expense, higher gain on foreign exchange and higher amount of doubtful debts recovered in 2Q20.

 
Table: SCGM's last 8 quarterly results

 
Graph: SCGM's last 39 quarterly results

Financial Position

SCGM's financial position is deemed adequate with current ratio at 1.26 times while gearing ratio is elevated at 0.87 time.

Valuation

SCGM (closed at RM1.56 yesterday) is now trading at a PE of 26X (assuming the last 2 quarters' EPS can be maintained for a full year).  At this PE, SCGM is deemed fully valued.

Technical Outlook

SCGM broke above its downtrend line at RM0.80 in September. After the breakout, SCGM began a steep uptrend which nearly doubled in price. Its immediate resistance will be from the horizontal line at RM1.60.


Chart 1: SCGM's weekly chart as at Dec 9, 2019 (Source: Malaysiastock.biz)


Chart 2: SCGM's daily chart as at Dec 9, 2019 (Source: Malaysiastock.biz)

Conclusion

Based on improved financial performance & bullish technical outlook, SCGM is a good stock for long-term investment.

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.
Tuesday, October 01, 2019

LBALUM: Improved Earnings Not Reflected in Share Prices

Results Update

For QE31/7/2019, LBAlum's net profit rose 72% q-o-q & y-o-y to RM4.6 million while revenue was mixed-  up 12% q-o-q but down 7% y-o-y to RM127 million. Revenue rose 12% q-o-q mainly due to higher sales volume. Profit from operations increased by 126.6% q-o-q in line with the increase in revenue. After accounting for a drop in the share of results from an associate which decreased from RM1.80 million to RM0.95 million and a net other operating expenses of RM37,000 as compared to net other operating income of RM235,000 in the preceding quarter, the Group’s profit before taxation and profit after taxation for the current quarter both increased by 72% q-o-q. (Note: My first post on this stock is here.)


Table: LBAlum's last 8 quarterly results


Graph: LBAlum's last 47 quarterly results

Financial position

LBAlum's financial position as at 31/7/2019 is deemed satisfactory with current ratio at 1.4x and gearing ratio at 0.7x.

Valuation

LBAlum (closed at RM0.51 yesterday) is now trading at a trailing PE of 9 times (based on last 4 quarters' EPS of 5.7 sen). At this PE, LBAlum is fairly valued.

Technical Outlook

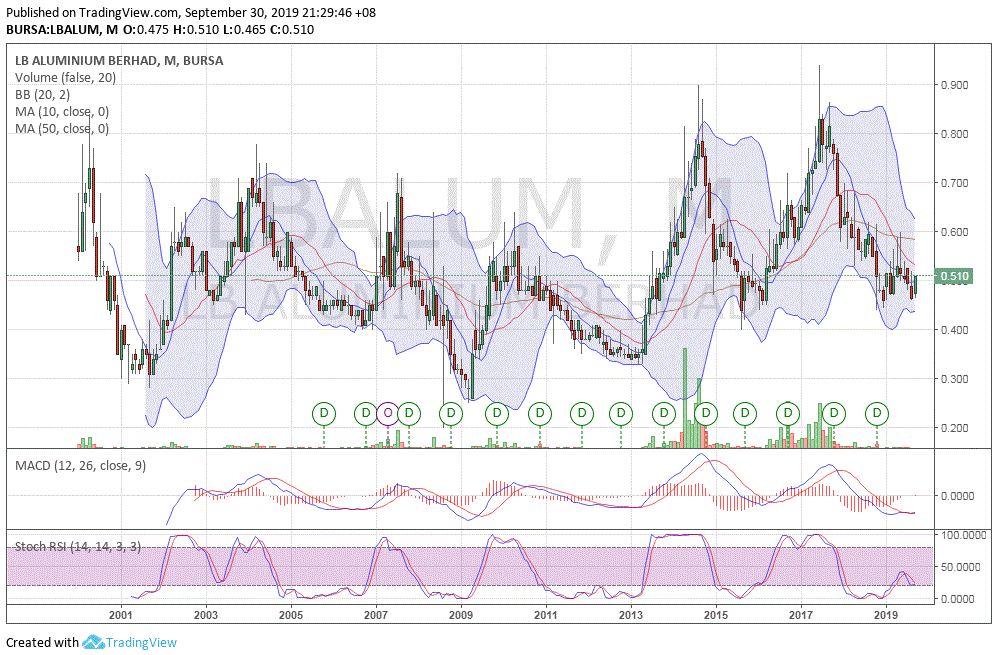
Over the past 18 years, LBAlum seems to be range-bound with an upward bias. The current range would be between RM0.45 & RM0.90. Since the prices are nearer the bottom of the range and the earnings have improved over the past 5 quarters, there is a good chance that the share price has bottomed.


Chart: LBAlum's monthly chart as at Sep 30, 2019 (Source: Malaysiastock.biz)

Conclusion

Based on improved financial performance & fair valuation, LBAlum could be a good stock for a recovery play. 

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Monday, September 30, 2019

Astino: Earnings dropped q-o-q

Result Update

In QE31/7/2019, Astino's net profit dropped 35% q-o-q but rose 131% y-o-y to RM5.5 million while its revenue rose 8% q-o-q or 19% y-o-y to RM153 million. Revenue increased q-o-q primarily due to increase in local market demand. The Group registered a profit before taxation of RM7.3 million, a decrease of RM3.6 million as compared to QE3/4/2019, which was recorded at RM10.9 million, mainly due to allowance for diminution in value of inventories was RM5.0 million higher than the immediate preceding quarter.


Table: Astino's last 8 quarters' results


Graph: Astino's last 49 quarters' results

Financial Position

Astino's financial position as at 31/7/2019 is deemed healthy with current ratio at 2.1x and gearing ratio at 0.4x.

Valuation

Astino (closed at RM0.71 last Friday) is now trading at a trailing PER of 8.2x (based on last 4 quarters' EPS of 8.7 sen). At this PER, Astino is deemed fairly valued.

Technical Outlook

Astino has broken above its downtrend line at RM0.65 in early September.


Chart: Astino's weekly chart as at Sep 27, 2018 (Source: Malaysiastock.biz)

Conclusion

Despite the weaker financial performance, Astino could be a good stock for long-term investment based on satisfactory financial position and fair valuation. The stock has a mildly bullish technical outlook after it broke above its downtrend line.

Note:

I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.

Friday, September 27, 2019

Scientx: Earnings Soared

Result Update

For QE31/7/2019, Scientx's net profit rose 83% q-o-q or 51% y-o-y to RM133 million while revenue was rose 13% q-o-q or 28% y-o-y to RM939 million. The increase in revenue and profits were contributed by better sales performance from both the manufacturing and property divisions.


Table: Scientex's last 8 quarterly results


Graph: Scientex's last 56 quarterly results

Financial Position

As at 31/7/2019, Scientex's financial position is deemed satisfactory with current ratio at 1.3 times and gearing ratio at 0.7 time.

Valuation

Scientex (closed at RM8.89 yesterday) is now trading at a trailing PE of 13.4 times (based on last 4 quarters' EPS of 66.26 sen). At this PER, Scientex is deemed fairly attractive.

Technical Outlook

Scientx was in an uptrend line, SS with support at RM8.00. Its upside is capped by the intermediate downtrend line, RR at RM9.20. An upside breakout above RM9.20 could signal the continuation of its uptrend.


Chart: Scientex's weekly chart as at Sep 26, 2019 (Source: Malaysiastock.biz)

Conclusion

Based on good financial performance, strong financial position, fairly attractive valuation and positive technical outlook, Scientex remains a good stock for medium to long-term investment.

Note:
I hereby confirm that I do not have any direct interest in the security or securities mentioned in this post. However, I could have an indirect interest in the security or securities mentioned as some of my clients may have an interest in the acquisition or disposal of the aforementioned security or securities. As investor, you should fully research any security before making an investment decision.