Thursday, February 25, 2016

Innity: The Next Jobstreet??

Background

Innity Corporation Bhd (Innity) is involved in the provision of online advertising solutions. According to Warren Raisch - quoting from GO-gulf.com - global online advertising is expected to grow to 18% of 2016's total advertising spending from 13% in 2011. At the same time, the online advertising in US is expected to grow from 25% to 37% of total advertising spending. For more go here.


Diagram 1: Global & US's Online Ad Spending

Experienced & Committed Shareholders

The shareholders of Innity include D.A. Consortium Inc, which is the online advertising specialist within the Hakuhodo DY Group of Japan. Hakuhodo is one of the world's leading advertising & marketing groups. In addition, it also counts Jobstreet Corp Bhd as one of its major shareholders. As you may know, Jobstreet is one of the great success stories of Malaysia IT industry.

I have tabulated the shareholding structure of Innity below. Besides the reduction/change in percentage shareholding in 2013 to accommodate the entry of D.A. Consortium Inc as a shareholder, we can see that over the past 1 year, some shareholders have raised their shareholding. This led to further concentration of shares held by these 8 shareholders, from 80% in 2011 to 84% today.


Diagram 2: Innity's Shareholding Structure  

Results Update

I have appended below the latest results for Innity for QE31/12/2015. The most 2 important things to note are:
1) Revenue are on rise
2) Net profit at RM1.48 million has surpassed the high achieved in QE31/12/2013.


Table: Innity's last 8 quarterly results


Chart 1: Innity's last 31 quarterly results

Financial Position

As at 31/12/2015, Inniti's financial position is deemed healthy. Current ratio stood at 2.0 times while gearing ratio is negligible at 0.9 time.

Valuation

Innity (closed at RM0.44 as at 4:00pm today) is now trading at a PE of 20 times (based on last 4 quarters' EPS of 2.12 sen). While this PER is still very high, Innity could well on the cusp of sharp rise in its revenue and earnings. If so, the PER could easily drop back to much more manageable level.

Technical outlook

Innity is trapped within a long-term uptrend line (support at RM0.30) and an intermediate downtrend line (resistance at RM0.43). A convincing breakout above the RM0.50 could signal the start of the upleg for this stock.


Chart 2: Innity's monthly chart as at Feb 25, 2015_3.00pm (Source: ShareInvestor)

Conclusion

Based on the favorable advertising trend, satisfactory financial performance and strong financial position, Innnity is a stock worth investing for long-term. Those seeking a quick trade should look somewhere else because Innity is not a liquid nor an active stock which makes exit very challenging.

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Innity.

Hevea: Fantastic result!

Results Update

For QE31/12/2015, Hevea's net profit increased by 42% q-o-q or 188% y-o-y to RM26 million while revenue grew by 22% q-o-q or 31% y-o-y to RM151 million.

Revenue increased y-o-y contributed by  both  the  particleboard sector (due to higher  sales  of  higher grade products, increased sales in value added products and higher USD exchange rate to Ringgit during this reporting period) and RTA sector (due to process automation which resulted in higher productivity, efficiency and also the capability to produce higher value and wider range of products).

PBT increased y-o-y due mainly to better performance in the particleboard sector resulting from increased sale of higher value and value-added  products coupled with the strengthening of USD, and also achieving an unrealized exchange gain of RM 950,000 instead of  a  loss  of  RM3.3  million  for  the same quarter in FY2014.


Table: Hevea's last 8 quarterly results


Chart 1: Hevea's last 33 quarterly results

Corporate News

In January, Hevea share price tumbled sharply when there was a spate of allegations amde against the company. This includes non-payment of dividend by its substantial shareholder, quality problem of its products in South Korea & funny accounting of amount owing by related parties. All of these were addressed by the management (here). Except for the last item, I do not see these problems as serious red flags. Ingenious accounting treatment is always a no-no for investors and the last item may serve as a nagging issue for sometimes, notwithstanding the fact that the amount owing had been fully settled.
 
Valuation

Hevea (closed at RM1.40 yesterday) is now trading at a PE of 7.6 times (based on last 4 quarters' EPS of 18.4 sen. At this PER, Hevea is still deemed very attractive. It may command a PER of 10-12 times- giving the stock an upside of at least 30%.

Technical Outlook

Hevea has been on a strong uptrend since it broke above its long-term downtrend line, RR at RM0.23 in November 2013.


Chart 2: Hevea's monthly chart as at Feb 24, 2016  (Source: ShareInvestor)

The stock's immediate support is its 50-week EMA line at RM1.10. This was tested in January when the spate of allegations mentioned above surfaced. Despite the negative news, the stock held up very well and we can rely on this test as a guide in future trading of the stock.


 Chart 2: Hevea's weekly chart as at Feb 24, 2016  (Source: ShareInvestor)

Conclusion

Based on good financial performance, relatively attractive valuation & positive technical outlook, Hevea remains a good stock for long-term investment.

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Hevea.

CBIP: Earnings soared

Results Update

For QE31/12/2015, CBIP's net profit rose 162% q-o-q or 61% y-o-y to RM39 million while revenue was mixed; rose 59% q-o-q but dropped 4% y-o-y to 197 million. Revenue increased q-o-q due to higher project billing by special purpose vehicles and palm oil mill equipment segments. PBT rose q-o-q due mainly attributable to improvement in project implementation and management by the special purpose vehicles and palm oil mill equipment segments, and a favorable foreign exchange during the current quarter & 21%-increase in shares of results of associates.


Table 1: CBIP's last 8 quarterly results


Despite the sharp swing, one can see that CBIP's revenue and profit are rising in line with the steady growth in the palm oil estates. This is supportive of the management's expectation of satisfactory results for FY2016.


Chart 1: CBIP's last 36 quarterly results 

Valuation

CBIP (closed at RM2.15 yesterday) is now trading at a PE of 12.1 times (based on annualized EPS of 17.7 sen). At this multiple, CBIP is deemed fairly valued.

Technical Outlook

CBIP has recently broken above its downtrend line at RM2.05  as well as the horizontal line at RM2.10. Its immediate resistance is at the horizontal line at RM2.23 & beyond that, the horizontal line at RM2.40.


Chart 2: CBIP's weekly chart as at Feb 24, 2016 (Source: ShareInvestor)

Below we can see that CBIP is in a long-term "uptrend line" with support at RM1.80.


Chart 3: CBIP's monthly chart as at Feb 24, 2016 (Source: ShareInvestor)

Conclusion

Based on good financial performance,reasonable valuation & bullish technical outlook, CBIP is a good stock for long-term investment.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, CBIP.

Tuesday, February 23, 2016

CSCSTEL: Earnings rebounded

Results Update

CSCStel's net profit increased by 179% q-o-q to RM28.5 million. Revenue increased by 9% q-o-q to RM243 million due to significant increase in sales volume of some of its steel products and marginal increase in selling prices of some of its steel products. In line with the higher revenue and the write-back of the doubtful debt provision of RM16.9 million, profits soared. If the write-back is excluded, the profits would still have been significantly higher: 67%  for PBT and 20% for net profit.


Table: CSCStel's last 8 quarterly results


Chart 1: CSCStel's P&L for last 33 quarterly results

Valuation

CSCStel (closed at RM1.28 yesterday) has a PE multiple of 8.8 times (based the last 4 quarters' EPS of 14.5 sen). This plus its DY of 6.2% make CSCTEL a fairly attractive stock.

Technical Outlook

CSCStel broke above its intermediate downtrend line at RM1.10 in early January. Its immediate resistance is the horizontal line at RM1.30. Beyond that, it may encounter resistance at RM1.50-1.60.


Chart: CSCStel's monthly chart as at Feb 22, 2016 (Source: ShareInvestor.cm)

Conclusion

Based on the improved financial performance, fairly attractive valuation & positive technical outlook, CSCStel could be a good stock for long-term investment. 

Note: 
 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, CSCSTEL.

Boxpak: Earnings dropped due to goodwill write-off & forex losses

Result Update

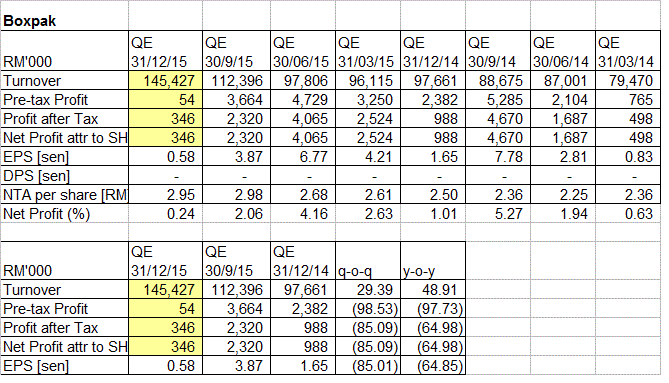
For QE31/12/2015, Boxpak's net profit dropped by 85% q-o-q or 65% y-o-y to RM346k while revenue rose by 30% q-o-q or 49% y-o-y to RM145 million.

Revenue rose q-o-q due to pre-festive season sales in Malaysia and Vietnam. Revenue continued its steady rise y-o-y due to increase in customers' demand in Vietnam and the relative strengthening of Vietnam Dong ("VND") against Ringgit Malaysia ("RM").

PBT dropped due to higher operating cost, the write-off of goodwill of RM2.4 million and foreign currency exchange loss of RM5.9 million. If the latter 2 one-off items are excluded, PBT would rise to RM7.3 million- an increase of 99% q-o-q or 2-fold increase y-o-y.


Table: Boxpak's last 8 quarterly results


Chart 1: Boxpak's last 33 quarterly results

Valuation

Boxpak (closed at RM2.50 yesterday) is now trading at a PE of 38 times (based on last 4 quarters' EPS of 15.43 sen). If the 2 one-off items are excluded, Boxpak's EPS would rise to 28 sen and its PER would drop to 9 times. Based on its adjusted PER, Boxpak is deemed quite attractive.

Technical Outlook

Boxpakbroke above the strong horizontal resistance at RM2.50 in October 2015. It made a high of RM3.10 in early November. Since then, the share price has retraced back to RM2.60-2.70.


Chart 2: Boxpak's monthly chart as at Feb 22, 2016 (Source: ShareInvestor.com)

Conclusion

Based on "good" financial performance and "fairly" attractive valuation, Boxpak is a good stock for long-term investment.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Boxpak

Friday, February 19, 2016

Hupseng: Eat Your Biscuits!

Background

Hup Seng Industries Bhd ('Hupseng') is involved in the manufacture and sales of biscuits, confectioneries & other foodstuffs.

Recent Financial Performance

For QE31/12/2015, Hupseng's net profit rose by 33% q-o-q or 22% y-o-y to RM15.4 million while revenue increased by 24% q-o-q or 9% y-o-y to RM80 million. The improved performance was attributed to higher biscuits sales in domestic and export market.

 
Table: Hupseng's last 8 quarters result

Historical Financial Performance

Hupseng's top-line and bottom-line as well as its profit margins have been in a slow & steady rise for the past 8-9 years.


Chart 1: Hupseng's last 8 quarters' P&L  

Financial Position

Hupseng's financial position as at 31/12/2015 is deemed healthy with current ratio at 2.5 times while total liabilities to total equity stood at 0.5 time. The company has no borrowing. Instead it has cash of RM120 million or RM0.15 per share.

Valuation

Hupseng (closed at RM1.32 yesterday) is now trading at a PER of 19 times (based on last 4 quarters' EPS of 6.84 sen). If the cash in hand is deducted from the share price, the PER would be lowered to 17 times. At this PER, Hupseng is deemed fairly valued.

Last year, Hupseng paid out dividend totaling 4.5 sen in 3 tranches. So far, it hd paid out dividend totaling 4 sen in 2 tranches this year. If it pays out a final dividend of 2 sen (equal to each one of the last 2 tranches), then Hupseng's DY would be a decent 4.5%.

Technical Outlook

Hupseng is in an intermediate uptrend line, with support at RM1.25. That uptrend line stretches back all the way to 2008 when it was trading at a low of RM0.05!! Since it has come a long way, the market is waiting for a compelling fundamental reason to buy into the stock. In the absence of a compelling reason to sell, the share price would likely to keep drifting higher.


Chart 2: Hupseng's weekly chart as at Feb 18, 2016 (Source: ShareInvestor.com)

 
Chart 3: Hupseng's monthly chart as at Feb 18, 2016 (Source: ShareInvestor.com)

Conclusion

Based on good financial performance, healthy financial position & positive technical outlook, Hupseng is a good stock for long-term investment. Good entry to the stock is when the share price drifts down to the uptrend line, currently at RM1.25.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Hupseng.

Thursday, February 18, 2016

Genting: Positve technical signs

Market Observation

Over the past 3 weeks, we have seen a marked increase in the trading volume for Genting-WA which coincided with the warrant trading above its horizontal resistance at RM1.00. Genting-WA - convertible at RM7.96 on a 1-for-1 basis & expiring on 18/12/2018 - has a slight premium of about 11%.


Chart 1: Genting-WA's weekly chart as at Feb 18, 2016_3.00pm  (Source: ShareInvestor)

Technical Outlook

Genting recovered after it had tested its long-term uptrend line at RM6.50-6.70 in August last year. Is this the beginning of its next upleg or a technical rebounce?


Chart 2:Genting's monthly chart as at Feb 18, 2016_3.00pm  (Source: ShareInvestor)

Looking at the weekly chart, we can see that Genting has broken to the upside of its ascending triangle at RM8.00. The weekly MACD, which had crossed above its signal line, is poised to go above the zero line. When that happens, Genting's upleg will begin in earnest.


Chart 3:Genting's weekly chart as at Feb 18, 2016_3.00pm  (Source: ShareInvestor)

Result Update

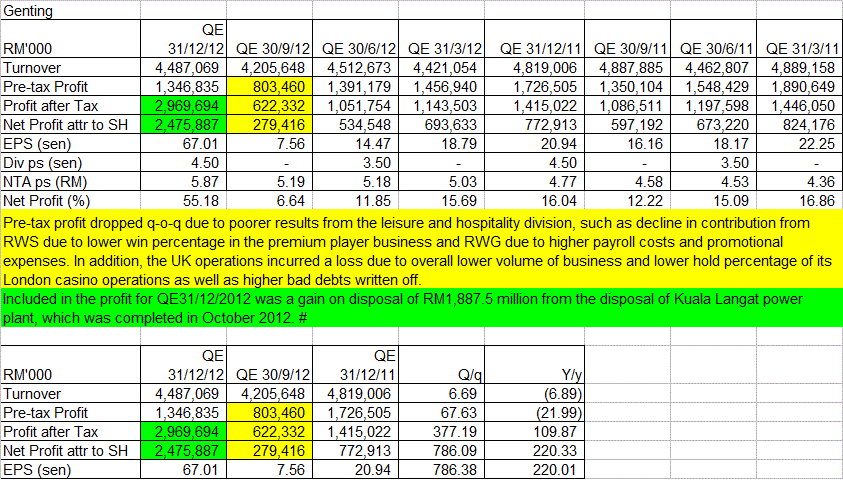
Genting's top-line has been fairly stagnant at about RM4-5 billion a quarter for the past 4 years. At the same time, its bottom-line has been drifting lower due to slipping profit margins.


Table: Genting's last 8 quarterly results


Chart 1: Genting's last 38 quarterly results

Valuation

Genting (at RM8.17 as at 4.35pm) is trading at a PE of 19  times (based on its last 4 quarters' EPS of 42 sen). At this PER, Genting is deemed fully valued.

Conclusion

Despite the unimpressive financial performance & demanding valuation, Genting could be a good stock to trading purpose due to the developing positive technical outlook. 

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Genting.

BAT: Earnings plunged

Result Update

For QE31/12/2015, BAT's net profit dropped by 24% q-o-q or 6% y-o-y to RM196 million while revenue dropped by 9% q-o-q or 12% y-o-y to RM1.06 billion. The revenue dropped sequentially due to a 19.4%-drop in Domestic and Duty Free sales volume as a result of a 36%-jump in excise duties. This is compounded by a 8.5%-drop in Contract manufacturing volumes. The sharply lower revenue plus increased costs & timing differences in expenditures resulted in a decline in Gross Profit of 15%. Higher expenses incurred as a result of trade retail contracts & brand initiatives added to the woes, which led to a 21.5%-decline in operating profits.


Table: BAT's last 8 quarterly results


Chart 1: BAT's last 36 quarterly results

Putting 4Q2015 in perspective

In the past, BAT's 4th quarters had shown poorer result due to two reasons: Firstly, the effect of higher sales in the immediate preceding quarter as retailers or stockists bought ahead of the budget where excise duties increase would normally be announced. Secondly, it is the quarter when lumpy expenditures are booked in.

The latest 4th quarter is no exception. If we plot the chart of the past 11 4th quarterly results, we can see that the trend of profits is up. Nonetheless, the sharp drop in revenue is very glaringly. That is the result of the unexpectedly huge jump in excise duties (off-budget!!) as well as a significant drop in Manufacturing contract. The domestic sales is expected to recover in the next few quarters- leading to the continuation of the uptrend for profits.


Chart 2: BAT's last 11 4th Quarterly results

Valuation

BAT (closed at RM56.08 yesterday) is now trading at a PE of 17 times (based on the last 4 quarters' EPS of 318 sen). BAT paid out a dividend of RM3.12 for the last 4 quarters; thus giving a Dividend Yield of 5.6%. At these PER & DY, BAT is deemed fairly attractive.

Technical Outlook

BAT is in an uptrend line, with support at RM55.00.


Chart 3: BAT's daily chart as at Feb 17, 2016 (Source: ShareInvestor)

Conclusion

Despite the poorer financial performance, BAT is still a good stock for long-term investment. Its valuation is fairly attractive and its technical outlook is still positive. Thus, I revise my rating for BAT from a HOLD to ACCUMULATE.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, BAT.

Wednesday, February 17, 2016

Gamuda-WR: Trading signals underlying bullish tone for Gamuda

For the past 4 days, we have seen the trading of the rights for Gamuda new warrant (likely to be named Gamuda-WE). This rights is referred to as Gamuda-WR which is currently trading at RM0.41. Based on the share price of RM4.42 presently, the premium of the new warrant would be about 6.6%. (Note: The new warrant exercise price is RM4.05 while the cost of subscription of the rights is RM0.25.)

When the rights of any instrument is traded, we would normally see arbitrage activity between the share and this rights. The arbitrage process for right issue of shares is pretty straight forward: You would sell the share if the net proceed is more than the cost of the rights (referred to as OR) plus the cost of subscription for this rights. When this scenario presents itself, you would sell the share and buy the rights and subscribe for the rights. However, the effect of this action -referred to as arbitrage- would be to cause the share price to go down and the OR price to go down until the last day of trading when some window-dressing activity would kick the price up momentarily at the close.

This principle can also be applied to the rights to subscribe for warrant (aka WR) in an indirect manner. Thus, a shareholder may sell the share and use the proceed to get some exposure in the stock via the warrant (Gamuda-WE) and take some cash off the table or alternatively he may use the entire proceed to get a larger exposure in the stock.

In the case of Gamuda new warrant, we can  see that investors or speculators are fairly enthusiastic in getting into this warrant (Gamuda-WE) as they began to buy on the 2nd day of the trading of the rights (Gamuda-WR). This is despite the fact that the share price continued to slide lower until yesterday. Thus, I believe that the share price has dropped sufficiently that we may well have seen a temporary bottom for the stock.

Based on the above, I believe that it is relatively safe to get into Gamuda now. For those with higher risk appetite and longer investment time horizon, you can consider buying Gamuda-WR and apply for the new warrant (Gamuda-WE).


Chart 1: Gamuda's 30-min chart as at Feb 17, 12016_ 9.25am (Source: ShareInvestor)


Chart 1: Gamuda-WR's 30-min chart as at Feb 17, 12016_ 9.25am (Source: ShareInvestor)

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Gamuda or Gamuda-WR.

Tasek: Another quarter of poor earnings

Results Update

For QE31/12/2015, Tasek's earnings continued to be weak, with net profit up 2% q-o-q but down 33% y-o-y to RM18 million while revenue rose 14% q-o-q or 9% y-o-y to RM188 million.Revenue rose due to higher volume of sales registered by both cement and ready-mixed concrete divisions. Nevertheless, the Group's current quarter profit after tax dropped y-o-y mainly due to lower profit margin from the cement segment arising from intense price competition in the domestic market and higher production cost. Lower interest income and lower share of profit from the Group's associated company during the quarter also affected the Group's profit for the reporting quarter.


Table: Tasek's last 8 quarterly results

Due to poorer results for the past 2 quarters, Tasek took the tough choice of reducing its dividend payout for the second quarters in a roll.

 
Chart 1: Tasek's last 31 quarterly results & dividend payout 

Valuation

Tasek (closed at RM14.84 yesterday) is now trading a PE of 19.8 times (based on last 4 quarters' EPS of 75 sen). At this PER, Tasek is deemed overvalued. With the decline in dividend payout, Tasek's DY dipped from of 11.5% to 7.4%. While still very respectable, the sharp drop may cause the stock to lose some of its long-term investors who bought into the stock for income.

Technical Outlook

The stock has tested its long-term uptrend line at RM14.50-15.00. With negative MACD reading and plunging stochastic, the near term outlook for Tasek is likely to be negative.


Chart 2: Tasek's monthly chart as at Feb 16, 2016 (Source: ShareInvestor.com)

If the stock breaks below the RM14.00, the uptrend could be over as this is probably the neckline of a developing Head and Shoulders formation. This will signal not only the end of the uptrend but the bearish reversal into a downtrend.


Chart 3: Tasek's weekly chart as at Feb 16, 2016 (Source: ShareInvestor.com)

Conclusion

Despite attractive dividend yield, Tasek is rated a SELL INTO STRENGTH based on demanding valuation and mildly negative technical outlook.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Tasek.

Harta: Earnings increased sequentially

Result Update

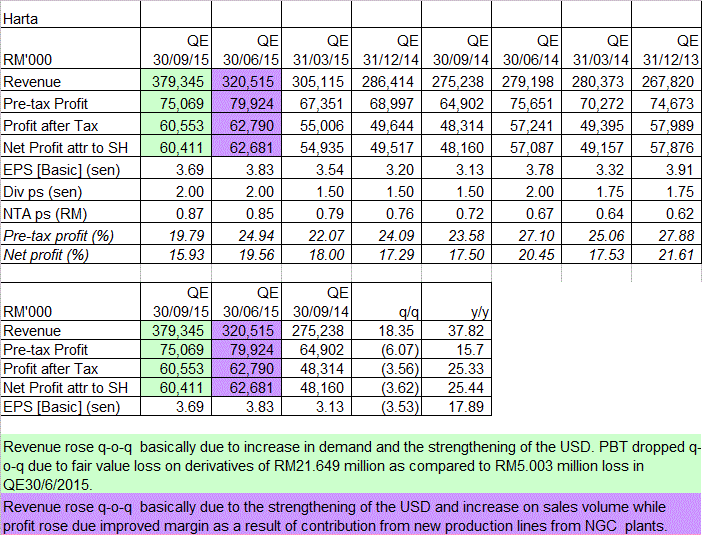
For QE31/12/2015, Harta's net profit rose by 20% q-o-q or 47% y-o-y to RM73 million while revenue rose 5% q-o-q or 39% y-o-y to RM398 million. Revenue rose q-o-q  basically due to increase in demand and the strengthening of the USD. This has more than offset the impact of competitive sale pricing and led to higher PBT. PBT also benefited from net forex gain of RM707k as compared to a net forex loss of RM19.988 million in the immediate preceding quarter.


 Table: Harta's last 8 quarterly results


Chart 1: Harta's last 33 quarterly results

Valuation

Harta (closed at RM4.98 yesterday) is trading at a trailing PER of 32 times (based on last 4 quarters' EPS of 15.49 sen). At this PER, Harta is deemed over-valued.

Technical Outlook

Harta is in a long-term uptrend over the past 6 years. Its long-term uptrend is well-supported by the 21-month EMA line at RM4.50 while its intermediate uptrend is supported by the 10-month SMA line at RM4.50.


Chart 2: Harta's monthly chart as at Feb 16, 2016 (Source: Share Investor)

Conclusion

Based on strong leadership in the rubber glove sector, good financial performance & capable management team, Harta is considered a good stock for long-term investment. However, the stock deserves only a rating of SELL INTO STRENGTH due to its demanding valuation.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, Harta.

Wednesday, February 10, 2016

MISC: Earnings rose due to early profit recognition

Results Update

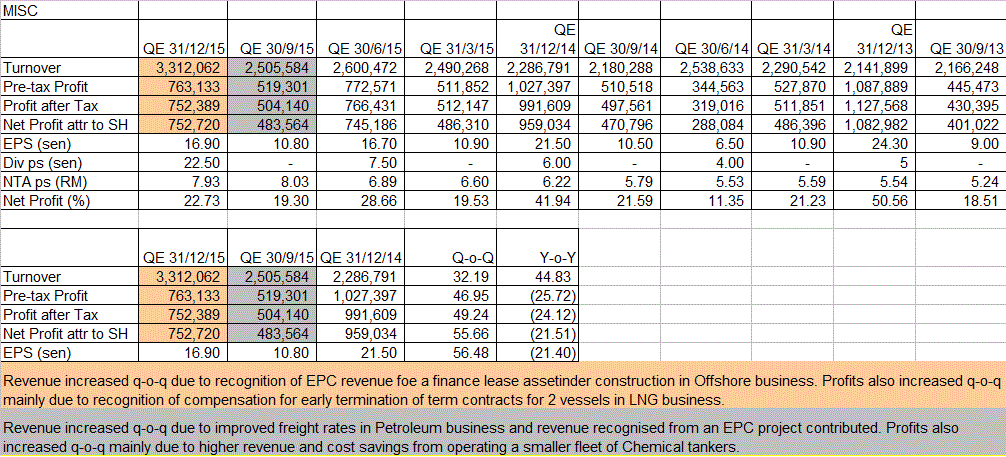
For QE31/12/2015, MISC's net profit increased by 56% q-o-q but dropped 22% y-o-y to RM753 million while revenue rose 32% q-o-q or 45% y-o-y to RM3.3 billion. Revenue increased q-o-q due to recognition of EPC revenue for a finance lease asset under construction in Offshore business. Profits also increased q-o-q mainly due to recognition of compensation for early termination of term contracts for 2 vessels in LNG business. The latter - being a compensation for contracts terminated- means that future earning will be affected. The former which could lead to early recognition of earning may "borrow" against future earning. Both of these would suggest that earning in the future could be lower than what's reported now.


 Table: MISC's last 8 quarterly results


Chart 1: MISC's last 38 quarterly results

Valuation

MISC (RM8.48 last Friday) is now trading at a PE of 15.4.times (based on last 4 quarterly EPS of 55 sen). At this PE, MISC is deemed fully valued.

Technical Outlook

MISC is in an uptrend line with support at RM8.30-8.40. If this support is violated, MISC may drop to its strong horizontal support at RM7.50.


Chart 2: MISC's weekly chart as at Feb 5, 2016 (Source: ShareInvestor.com)


Chart 3: MISC's monthly chart as at Feb 5, 2016 (Source: ShareInvestor.com)

Conclusion
Based on challenging outlook ahead and full valuation, MISC is a good stock to be avoided for now. For those who have the stock, you can only hope that the uptrend line support at RM8.30-8.40 would remain intact. Thus, MISC's rating is maintained as a HOLD.

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, MISC.

Sunday, February 07, 2016

Happy Chinese New Year


I like to wish all my Chinese readers a very happy and prosperous New Year. May the Year of the Monkey give you the agility and smartness to navigate the challenging year ahead. Gong Xi Fa Cai...


Source Scenicworld.com

Thursday, February 04, 2016

RCECap: Recovery continued

Result Update

For QE31/12/2015, RCECap's bottom-line continued to improve. Its net profit rose 27% q-o-q or 315% y-o-y to RM13.0 million on the back of higher revenue (up 6.4% q-o-q or 23.9% y-o-y to RM42 million). Net profit increased q-o-q mainly due to higher interest income by RM2.5 million


Table: RCECap's last 8 quarterly results

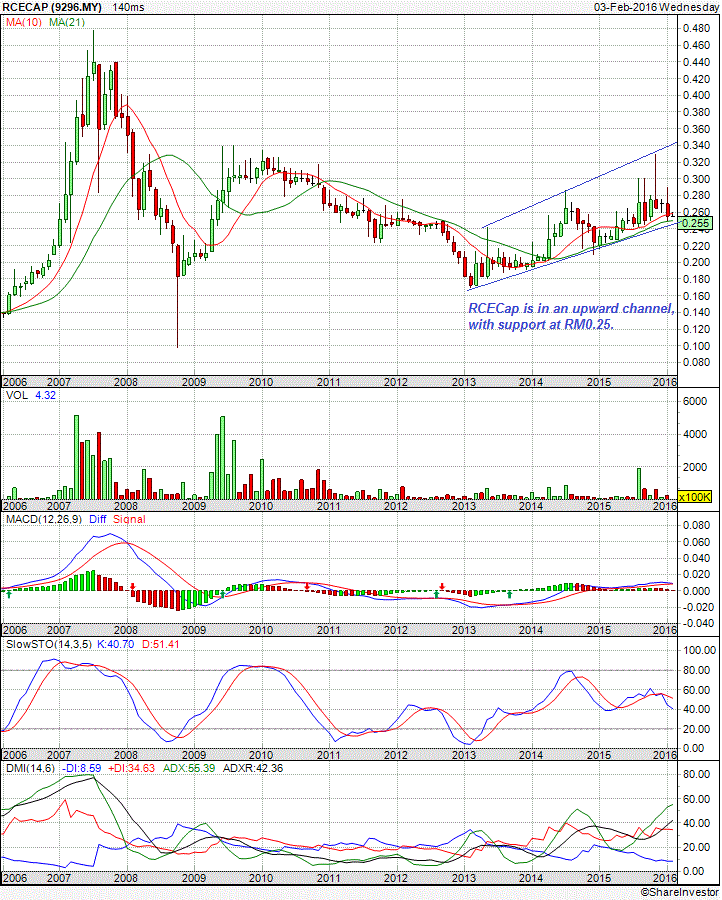
Looking at the Chart 1, we can see that RCECap's financial performance continued to crawl up after bottoming in last 2013.


Chart 1: RCECap's last 35 quarterly results

Valuation
RCECap (closed at RM0.255 yesterday) is now trading at a PE of 7.5 times (based on last 4 quarters' EPS of 3.42 sen). Price to book ratio stood at 0.7 time (based on NTA of RM0.35 per share).

Technical Outlook

RCECap is now rising in an upward channel with support at the lower line at RM0.25 and resistance at the upper line at RM0.35.


Chart 2: RCECap's monthly chart as at Feb 3, 2016 (Powered by ShareInvestor.com)

Conclusion

Based on improved financial performance, fair valuation & positive technical outlook, RCECap is good stock for long-term investment.

Note:
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, RCECap.

F&N: Earnings soared

Result Update

For QE31/12/2015, F&N's net profit rose jumped by 167% q-o-q or 117% y-o-y to RM152 million while revenue was up 4.5% q-o-q or 1.6% y-o-y to RM1.05 billion. Profits increased partly  attributed to higher revenue, effective product/sales mix (particularly on its main brands) and pricing management and favorable milk-based commodity prices, insurance claim of RM4.1 million (from the East Coast flood) and recovery of withholding on royalties paid in previous years of RM8.5 million. Even if the 2 last items are excluded, the recurring net profit would still be very impressive at RM139 million- an increase of 145% q-o-q or 99% y-o-y!!


Table: F&N's last 8 quarterly results


Chart 1: F&N's last 37 quarterly results

Valuation
F&N (closed at RM18.56 yesterday) is now trading at a PE of 19 times (based on last 4 quarters' EPS of 98.9 sen). At this PE multiple, F&N is deemed fairly valued.

Technical Outlook

F&N has been range-bound for the past 4 years between RM16.00 and RM19.00.A breakout of this trading range would determine the direction of the price movement going forward.


Chart 2: F&N's monthly chart as at Feb 3, 2016 (Source: ShareInvestor.com)

Conclusion

Based on strong improvement in its financial performance and less-demanding valuation, F&N is upgraded from a HOLD to a long-term BUY.

Note: 
In addition to the disclaimer in the preamble to my blog, I hereby confirm that I do not have any relevant interest in, or any interest in the acquisition or disposal of, F&N.